
Tele Columbus - Alternative Recap Scenario - Model Update
All,
Please find our updated analysis here.
Note: Beta testers can check tele Columbus on the portal here.
We will be updating the financials next.
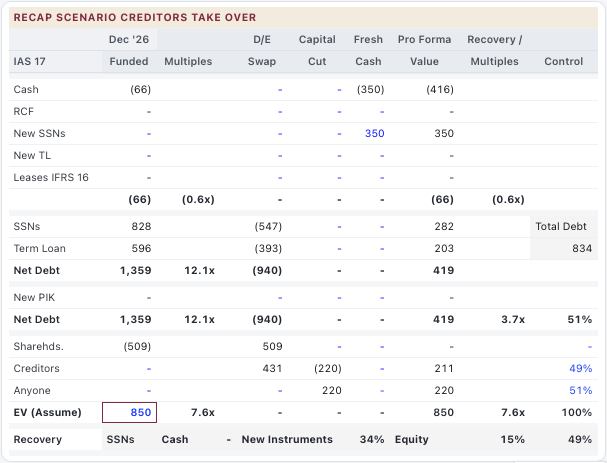
Considering recent developments, some of you have asked for another recapitalisation scenario involving another 350mn going in super senior. Please find the scenario on the Recapitalisation page under scenario 2.
Investment Rationale
At the recent price of 35, we remain neutral on the name. We would be inclined to go long if it were a good company with a bad balance sheet; however, it remains a fundamentally challenged company with a bad balance sheet and insufficient equity cushion.
TC is the lowest quality asset in the country and in a strategically unfavourable position. The 2023 strategy to invest in Telephony and Internet growth has failed decidedly, and all we'd be doing would be to try the same thing again. It will take quite possibly 2-3x more money than the €350m we think makes sense to throw at it in this round, and by then today's bond exposure will at best be the equity. It's a very uncertain equity bet for which we lack the required multi-year conviction.
To exit profitably in 2-3 years, we would have to enter at a 1x EBITDA discount to peers, which is well below the EV of €850m that we have used to rationalise the current state of discussions. Our analysis is based on an €850mn EV, which is a compromise but not supported by the company's FCF.
In summary, the ongoing need for substantial Capex and potential further layering, we are not comfortable yet holding this credit.
Morgan Stanley Exit Scenario
We previously outlined scenario 1 wherein MSIP retains control over Tele Columbus. In this scenario, bondholders would receive 30% of the equity after a haircut of 1/3.
In this new scenario, the Group's creditors take over from MSIP, and equity ratio is c. 50%, with net debt / EBITDA falling from 12.1x to 3.7x; the main creditors will become majority shareholders, while smaller creditors will still see a larger equity stake (to 49%) in comparison to scenario 1 (40%).
As a base case, we think the Group has a total debt-carrying capacity of €425m - due to the existing (and, in this scenario, written down) notes/loans being PIKed, Tele Columbus would be able to raise virtually all of the €425m in new money and still be able to service debt thus, we model €350m in new money.
All of this is used towards boosting liquidity but the key CoOp members (under 'Anyone' in the Recapitalisation table) are able to muscle some extra equity in for themselves in order to gain majority ownership of the company.
Recovery comes out to roughly 50c but we still don't see sufficient equity cushion for the risks here.
Happy to answer any questions if needed.
Regards,
Karan Pathak, CFA
E: kpathak@sarria.co.uk
T: +44 20 3192 0200
www.sarria.co.uk