- for speed listening, go to the settings wheel on the bottom right of the video and choose playback speed -
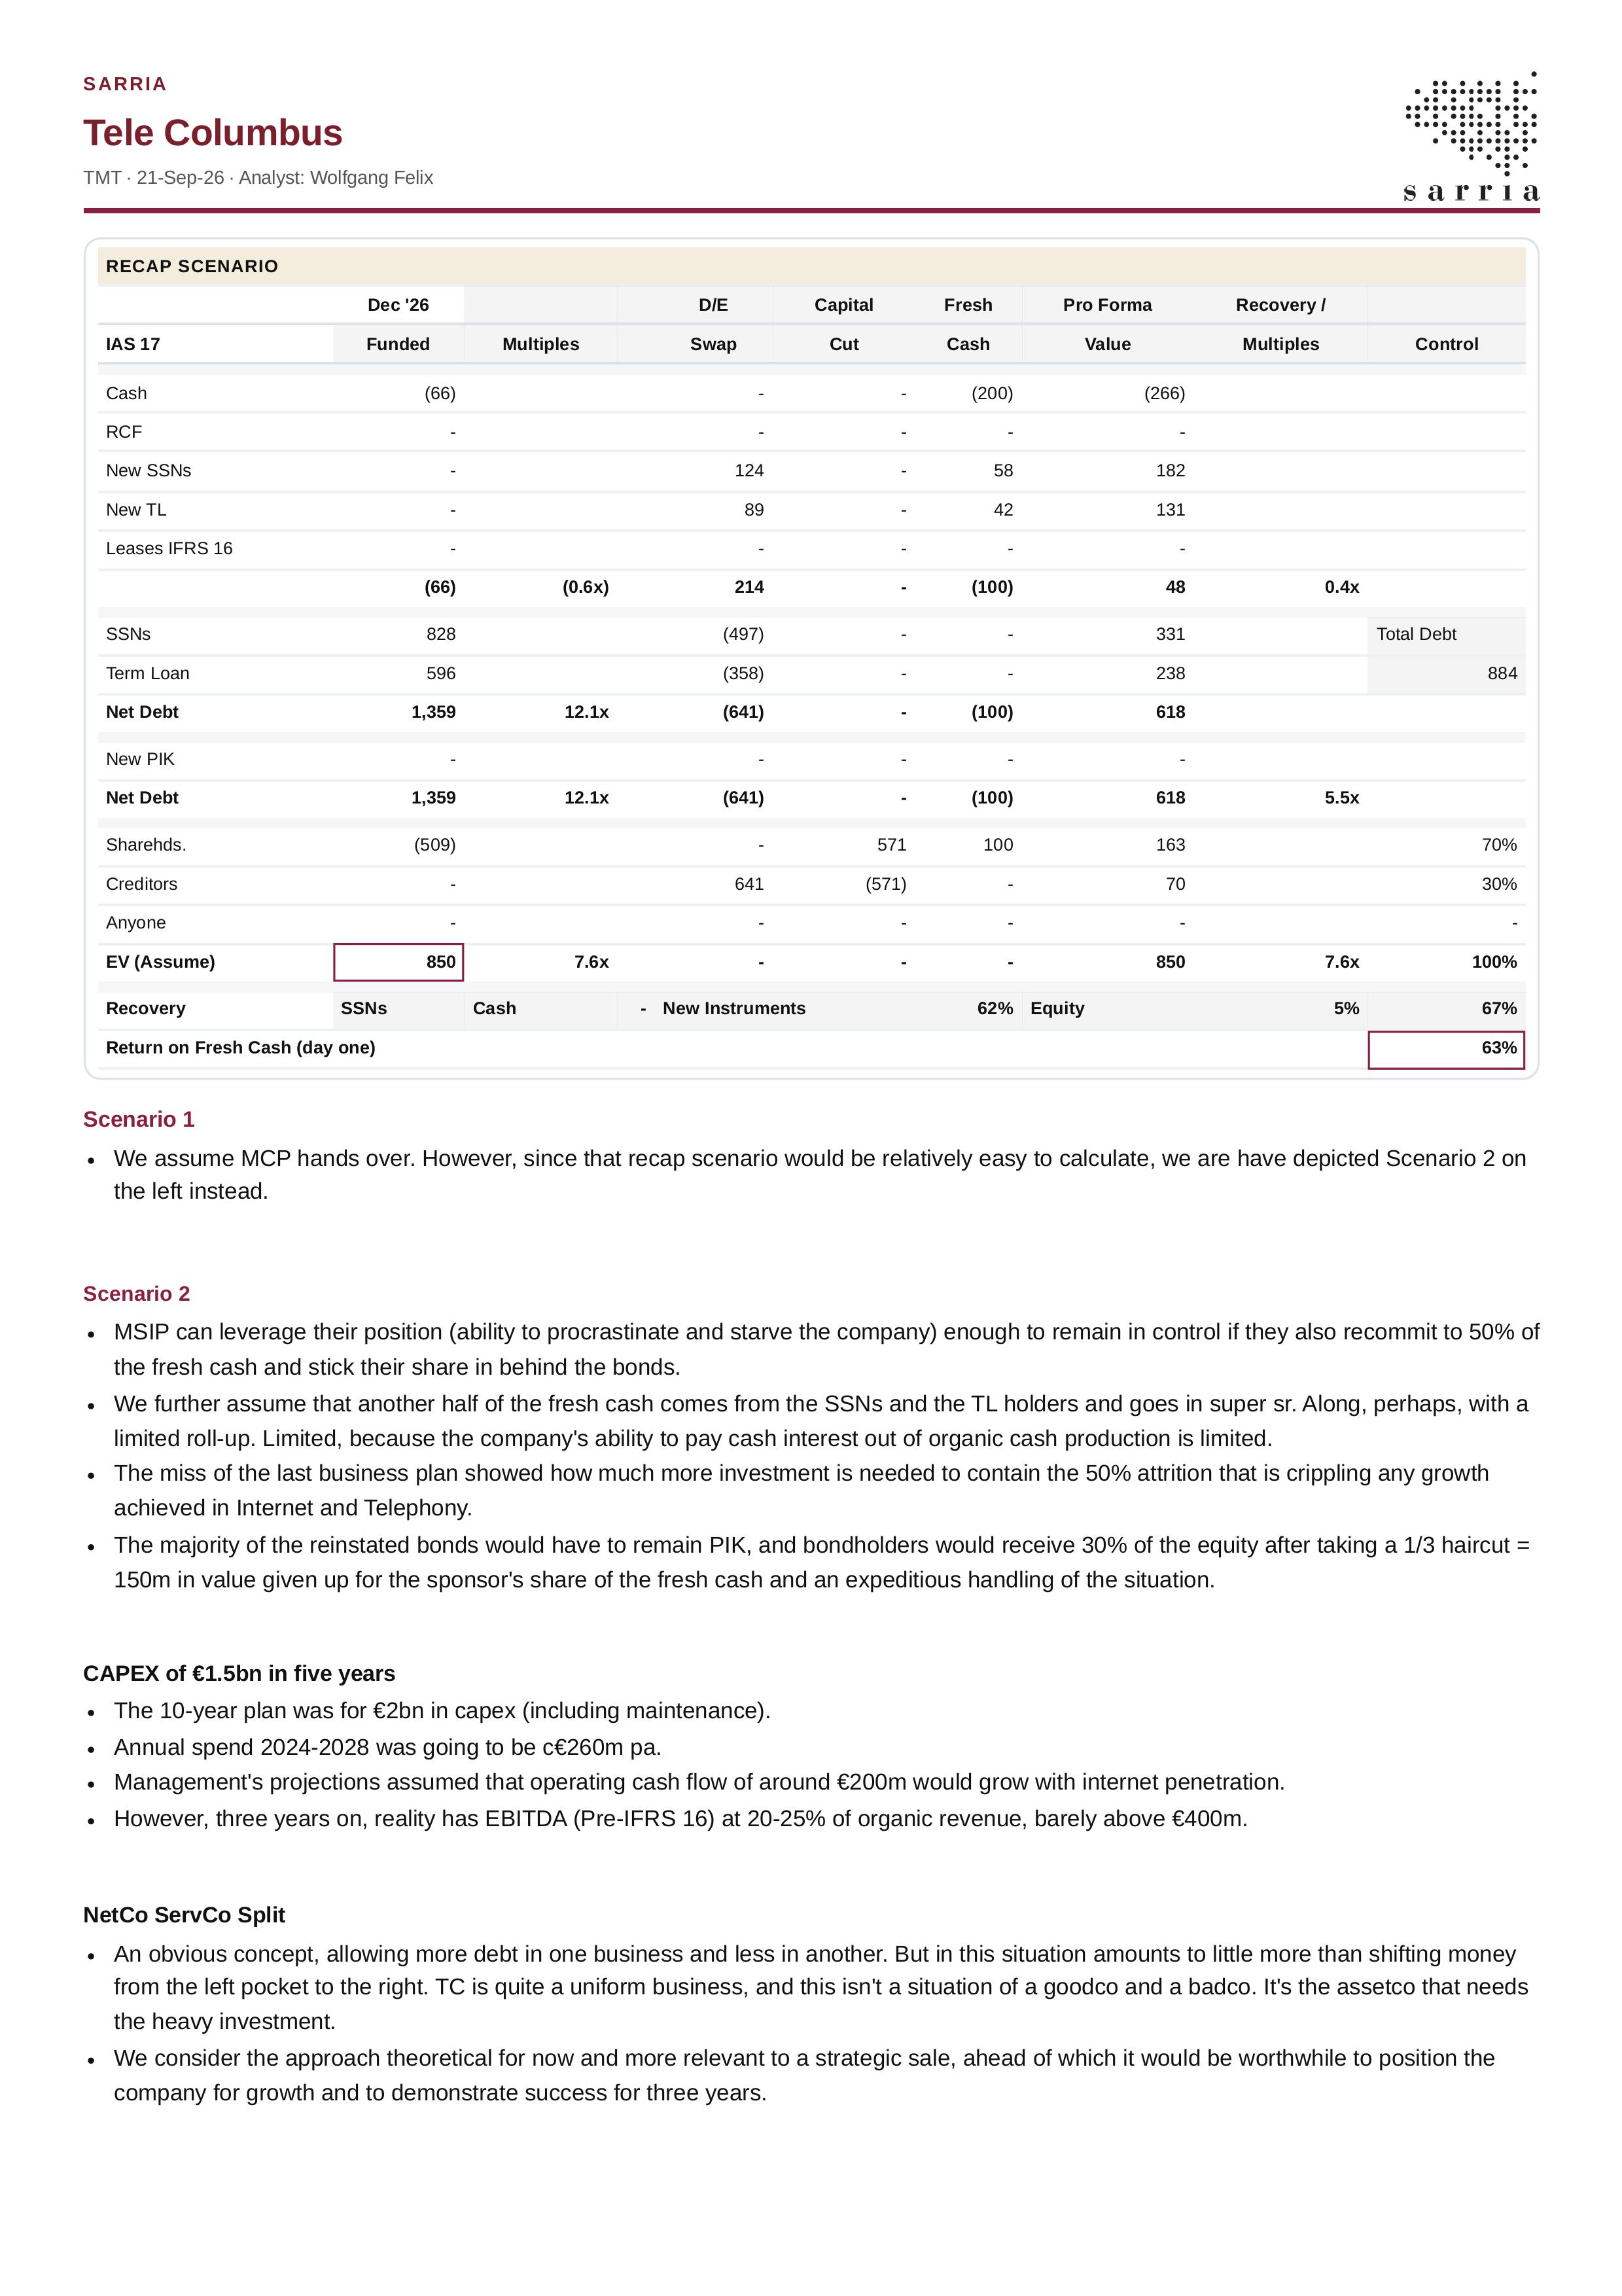
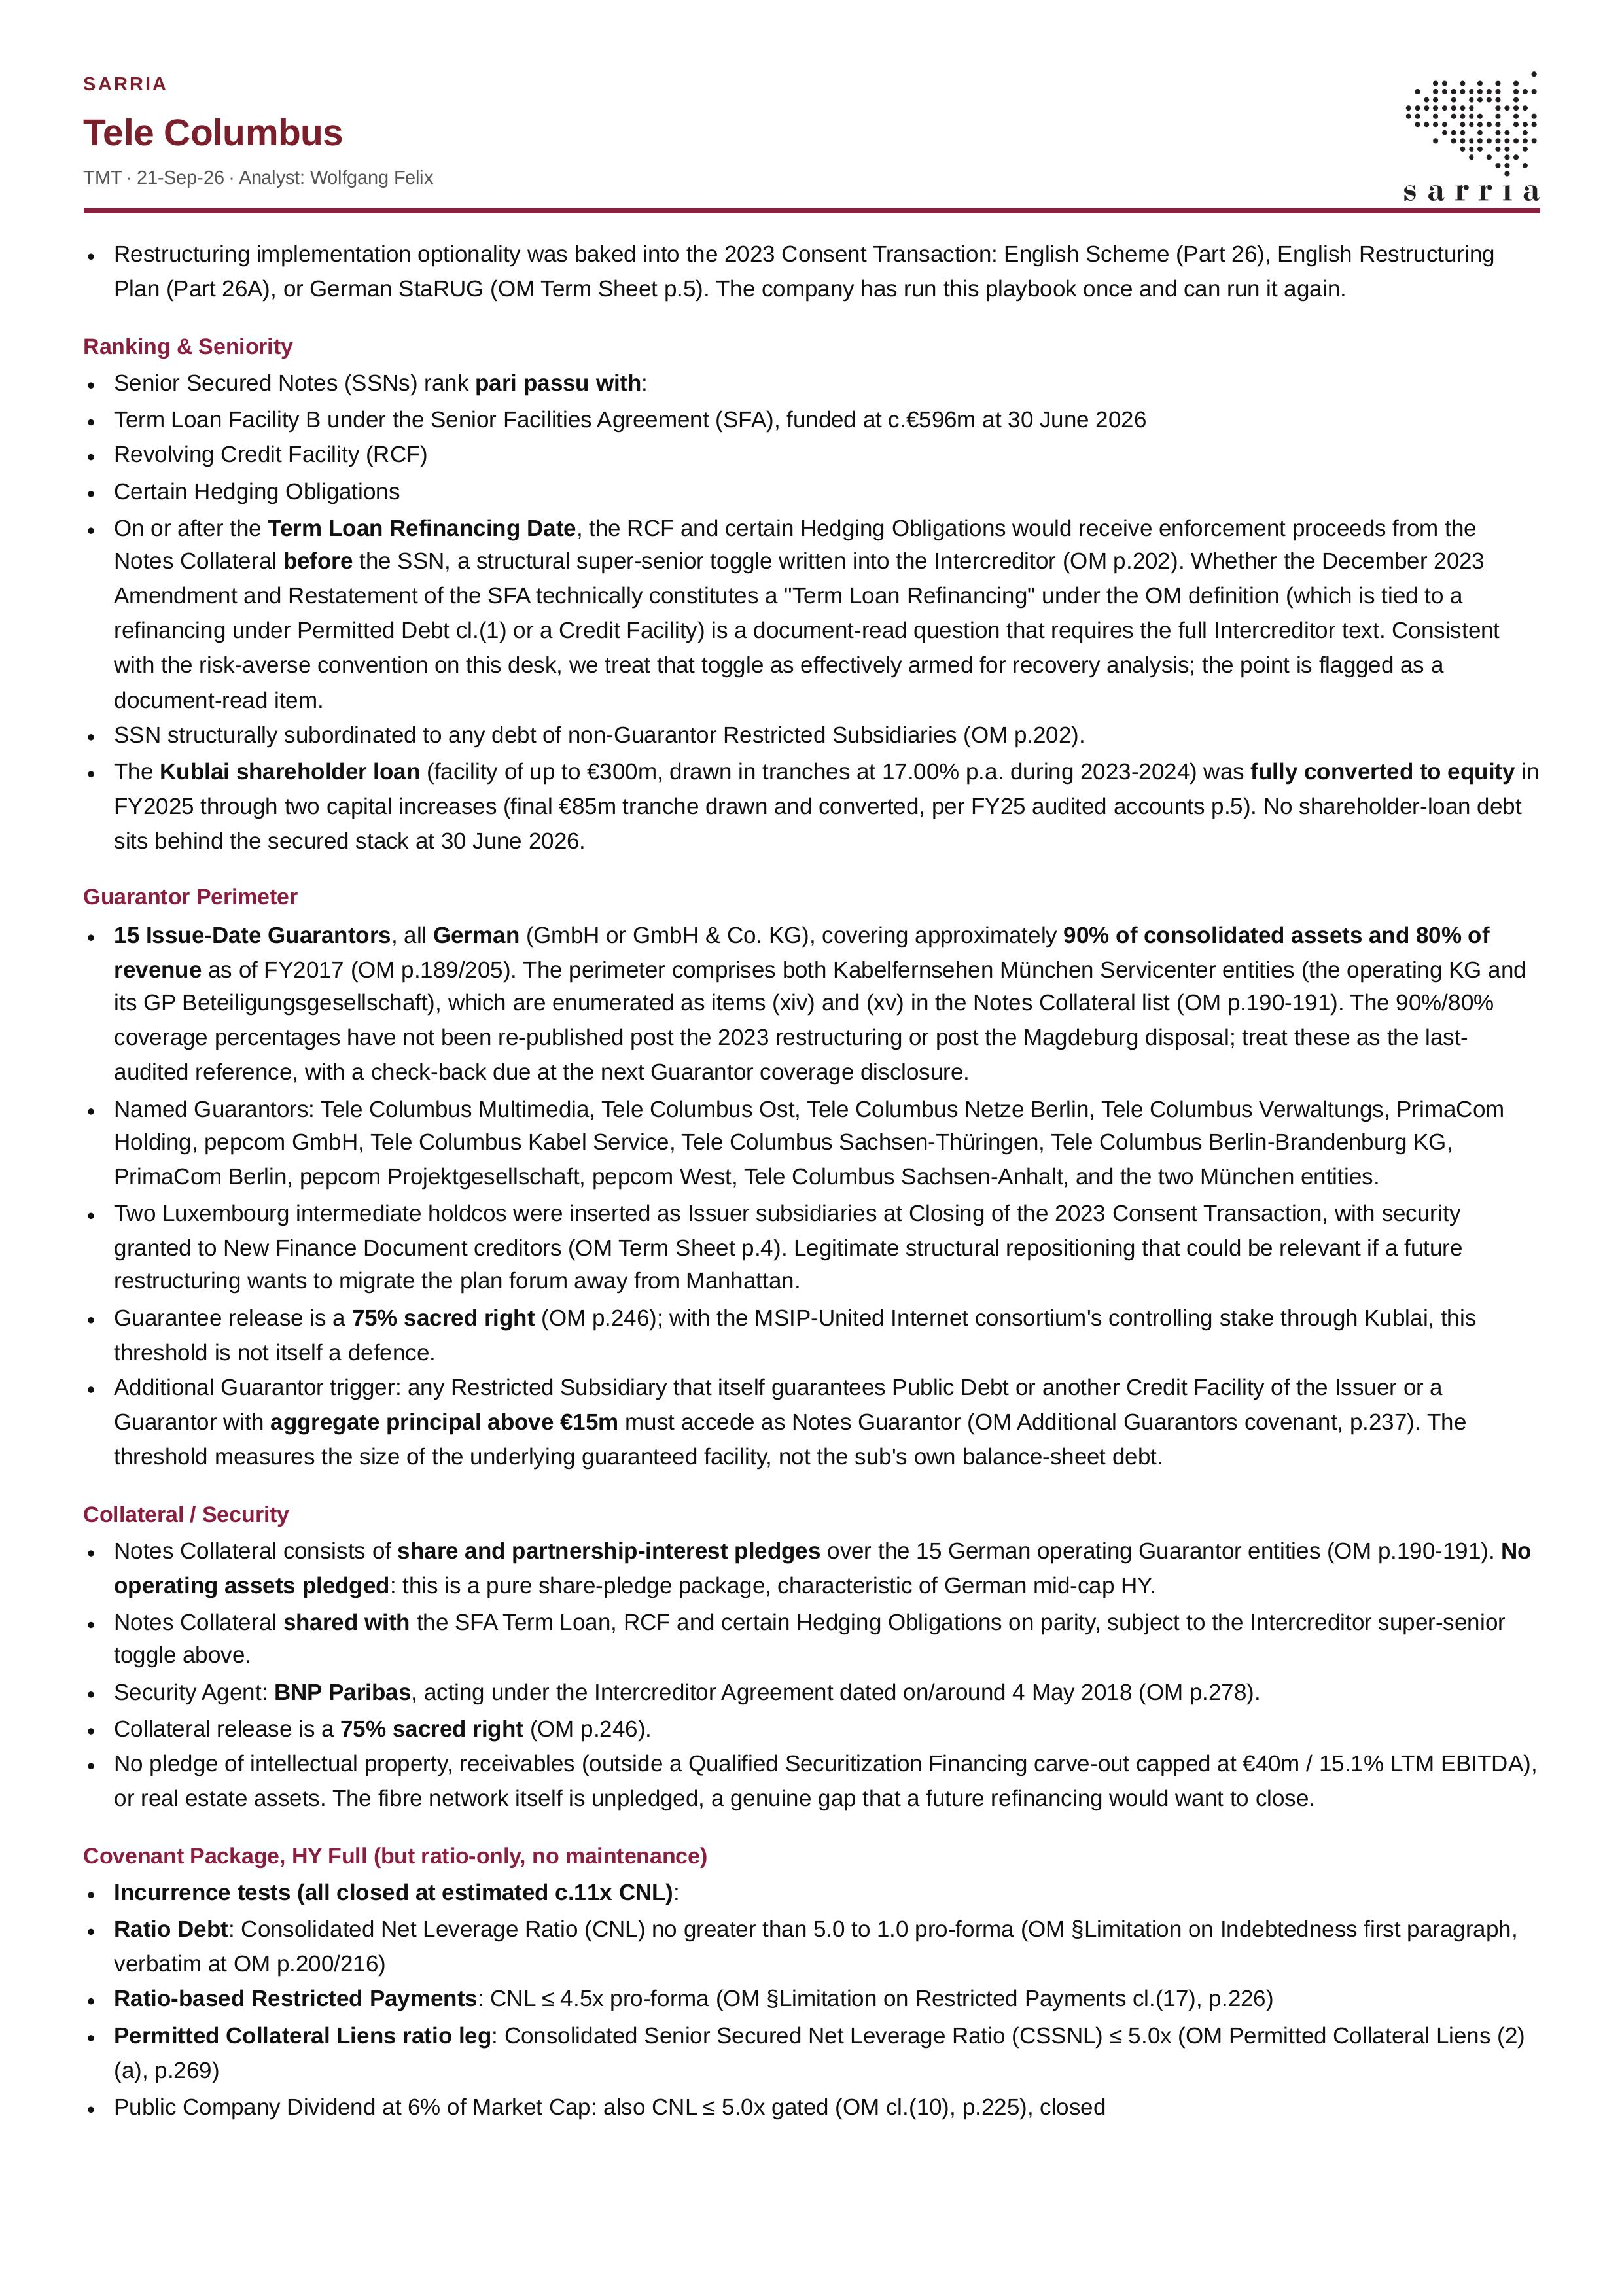
Intro, Legal and Cap Struct - 12 Sep 23
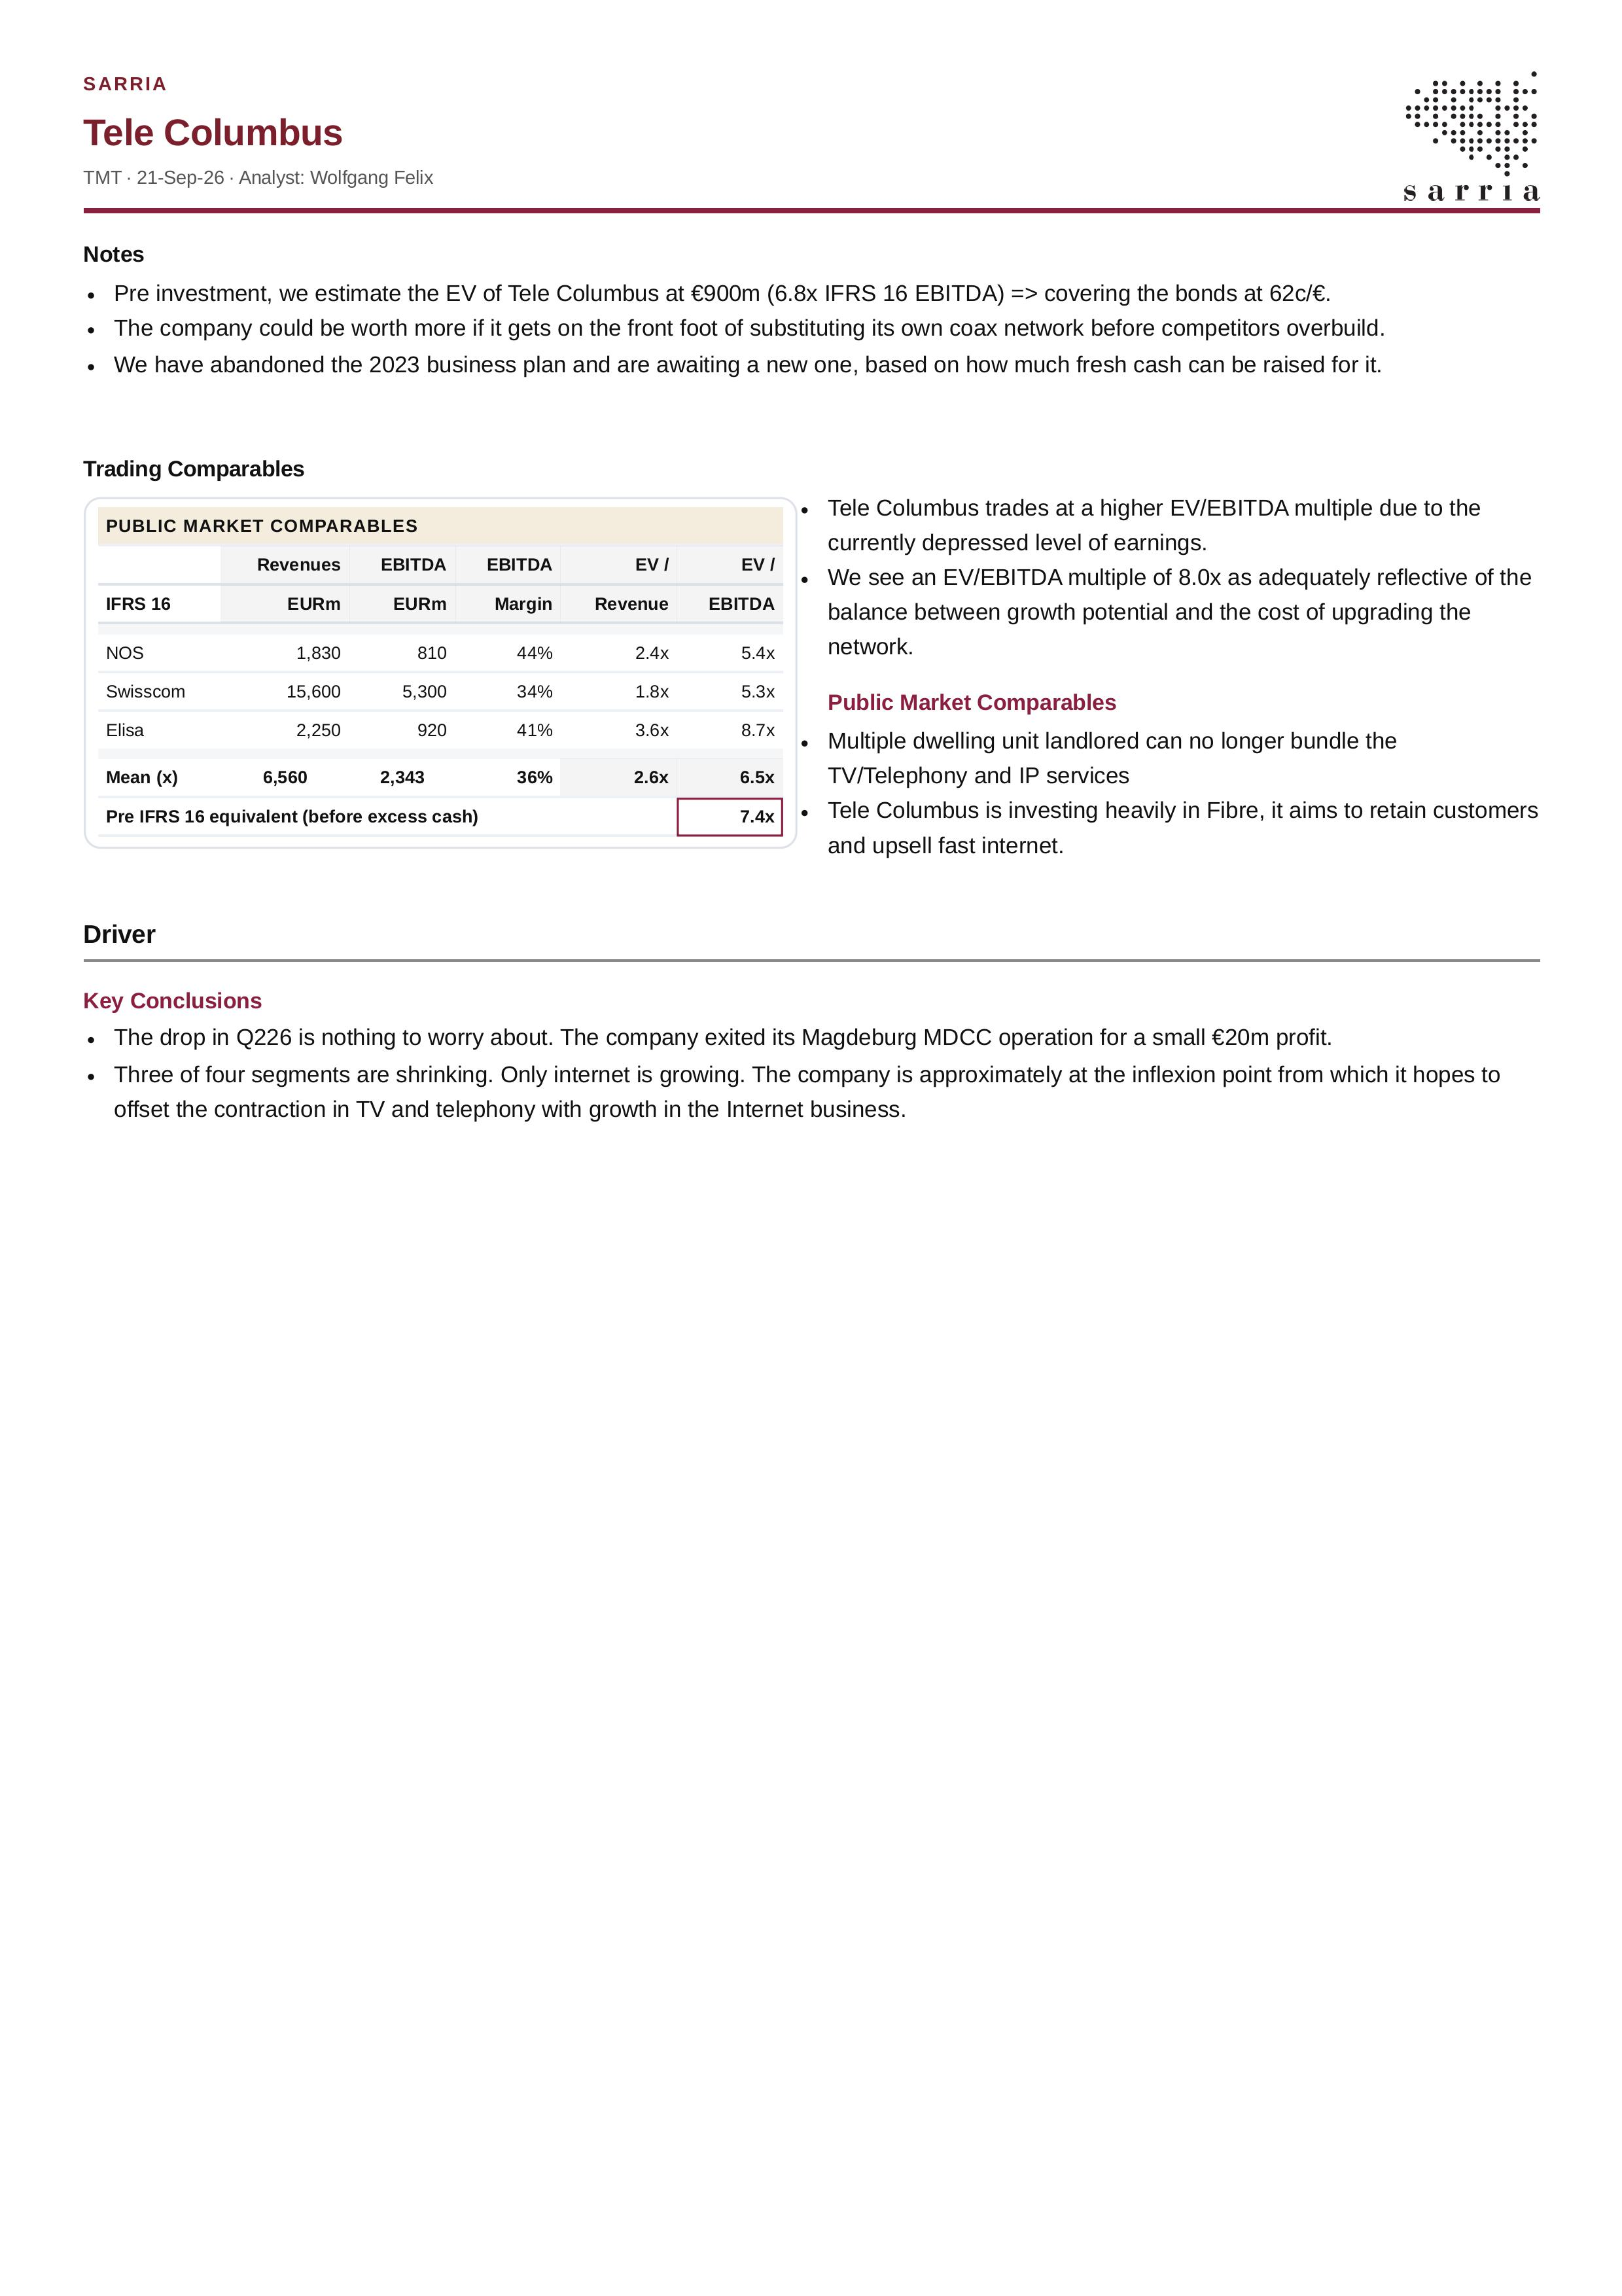
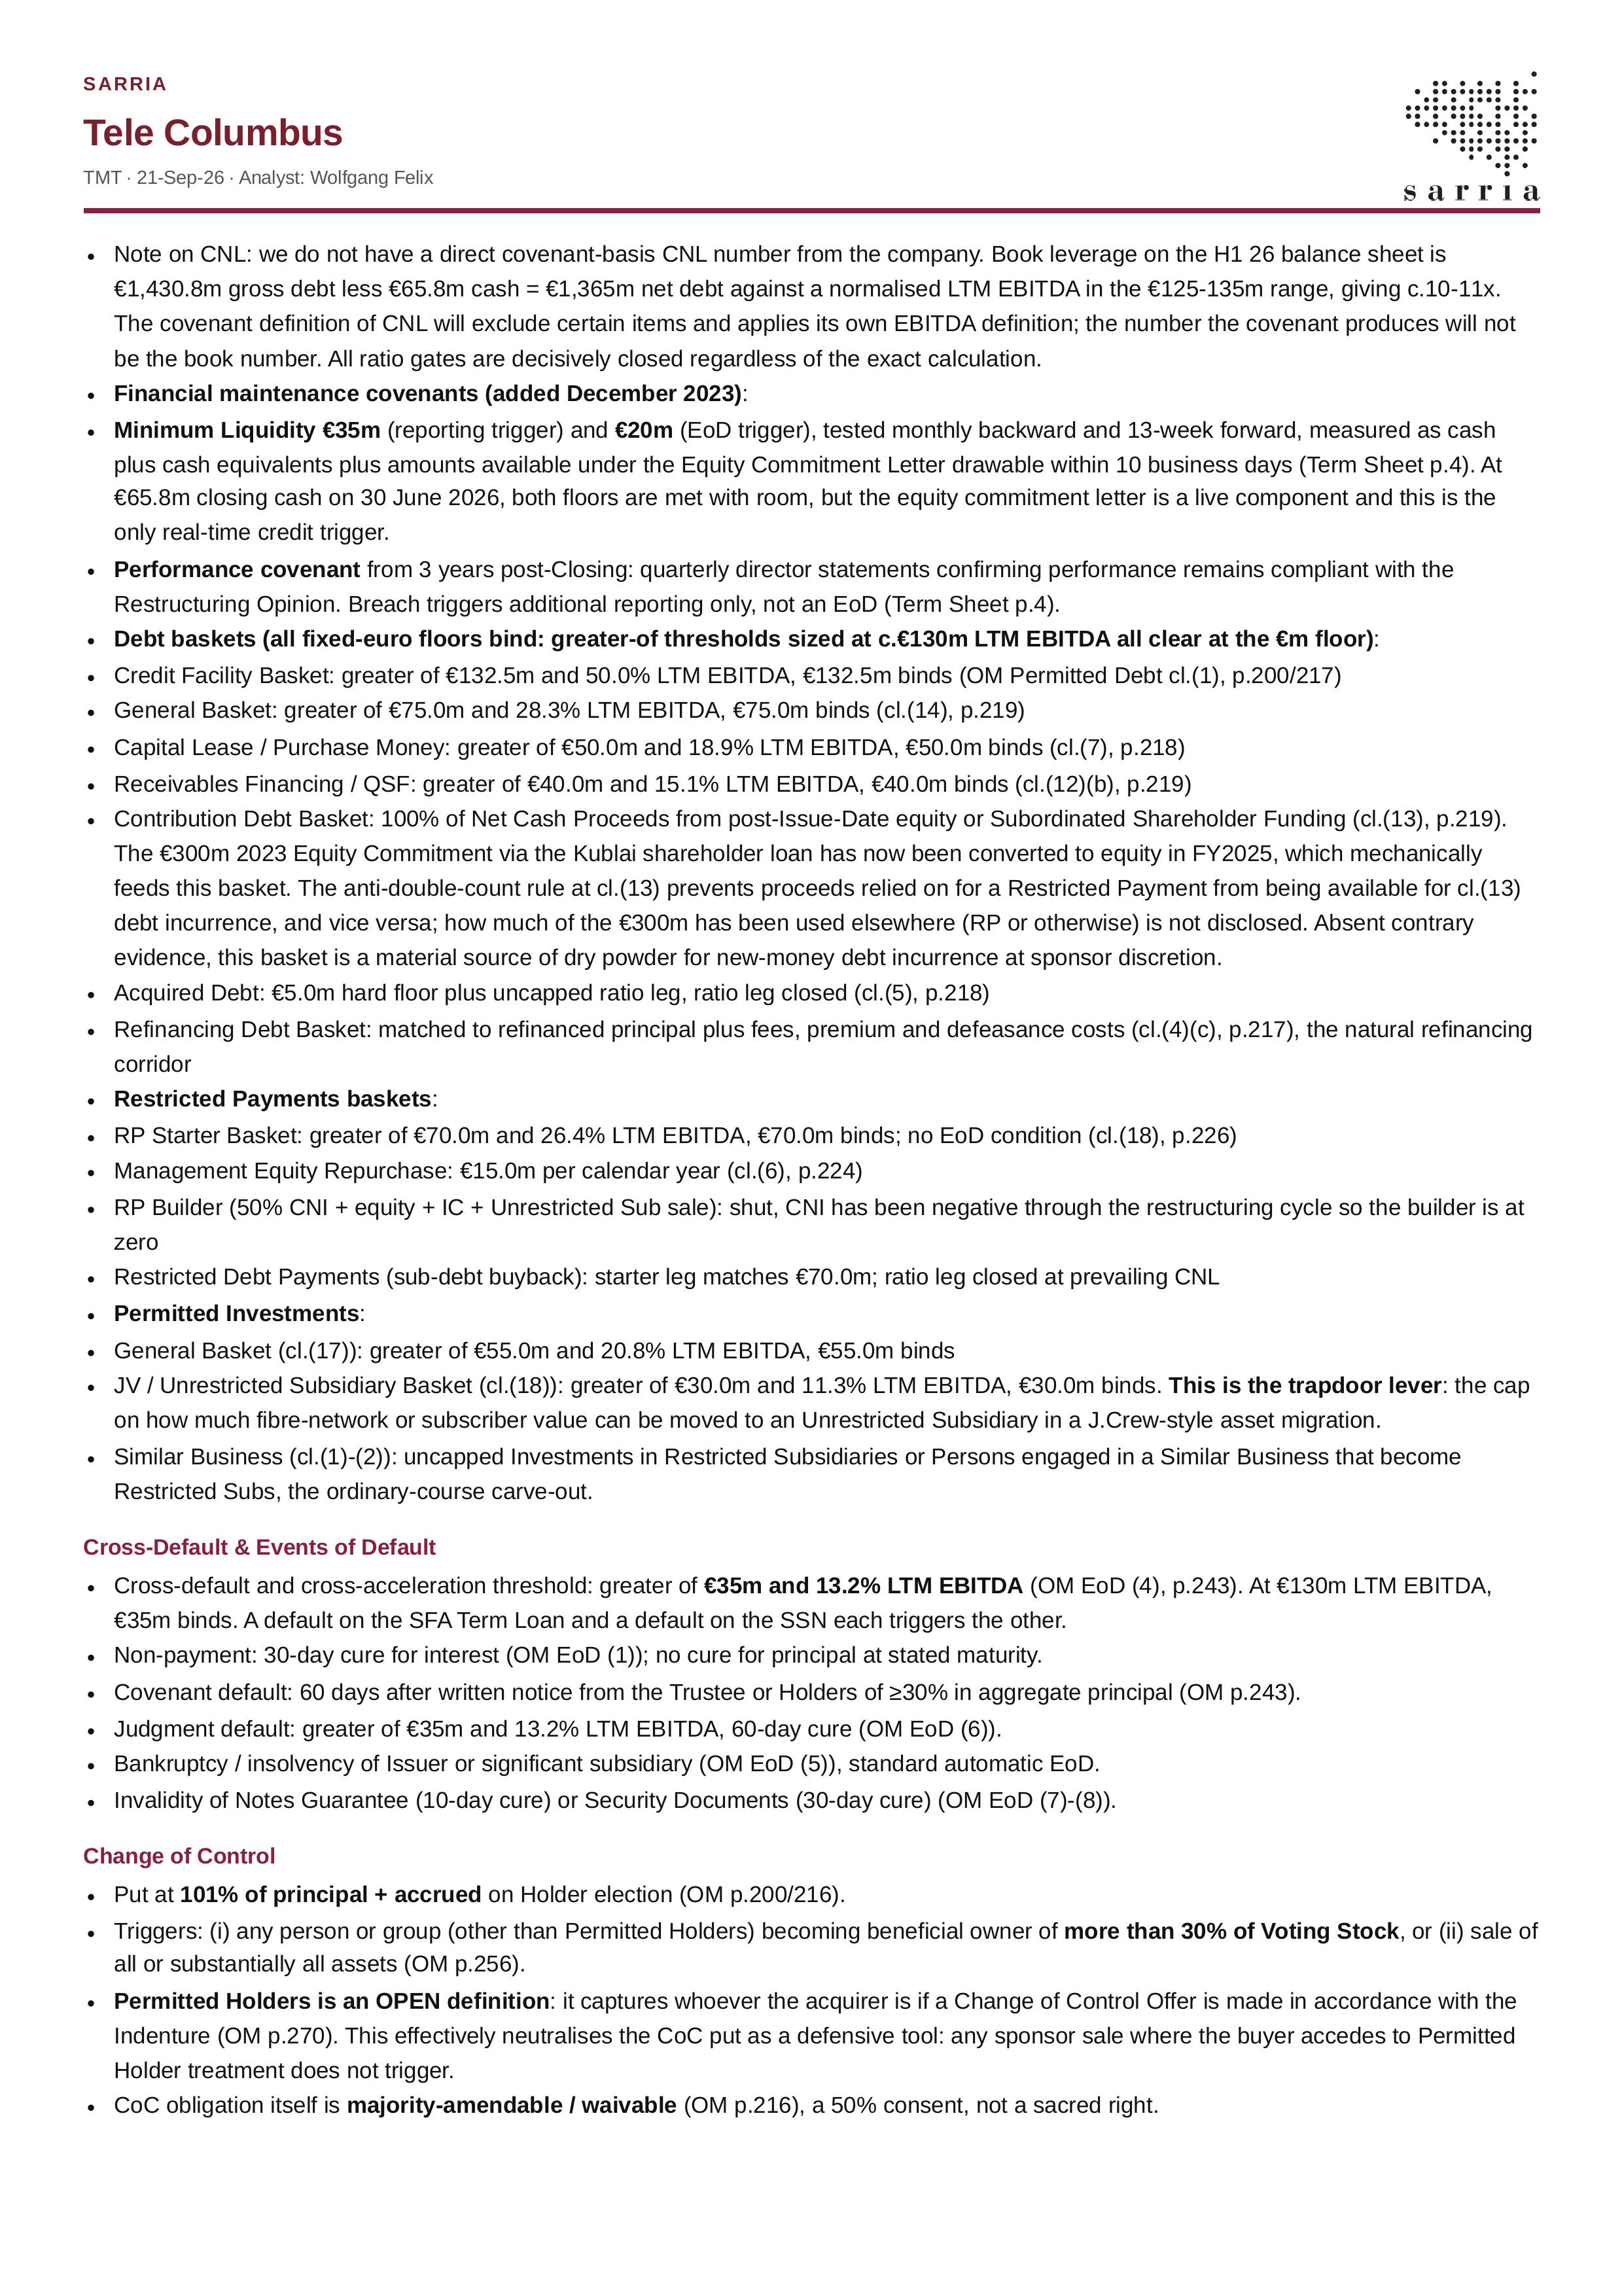
Business and Industry Overview - 12 Sep 23
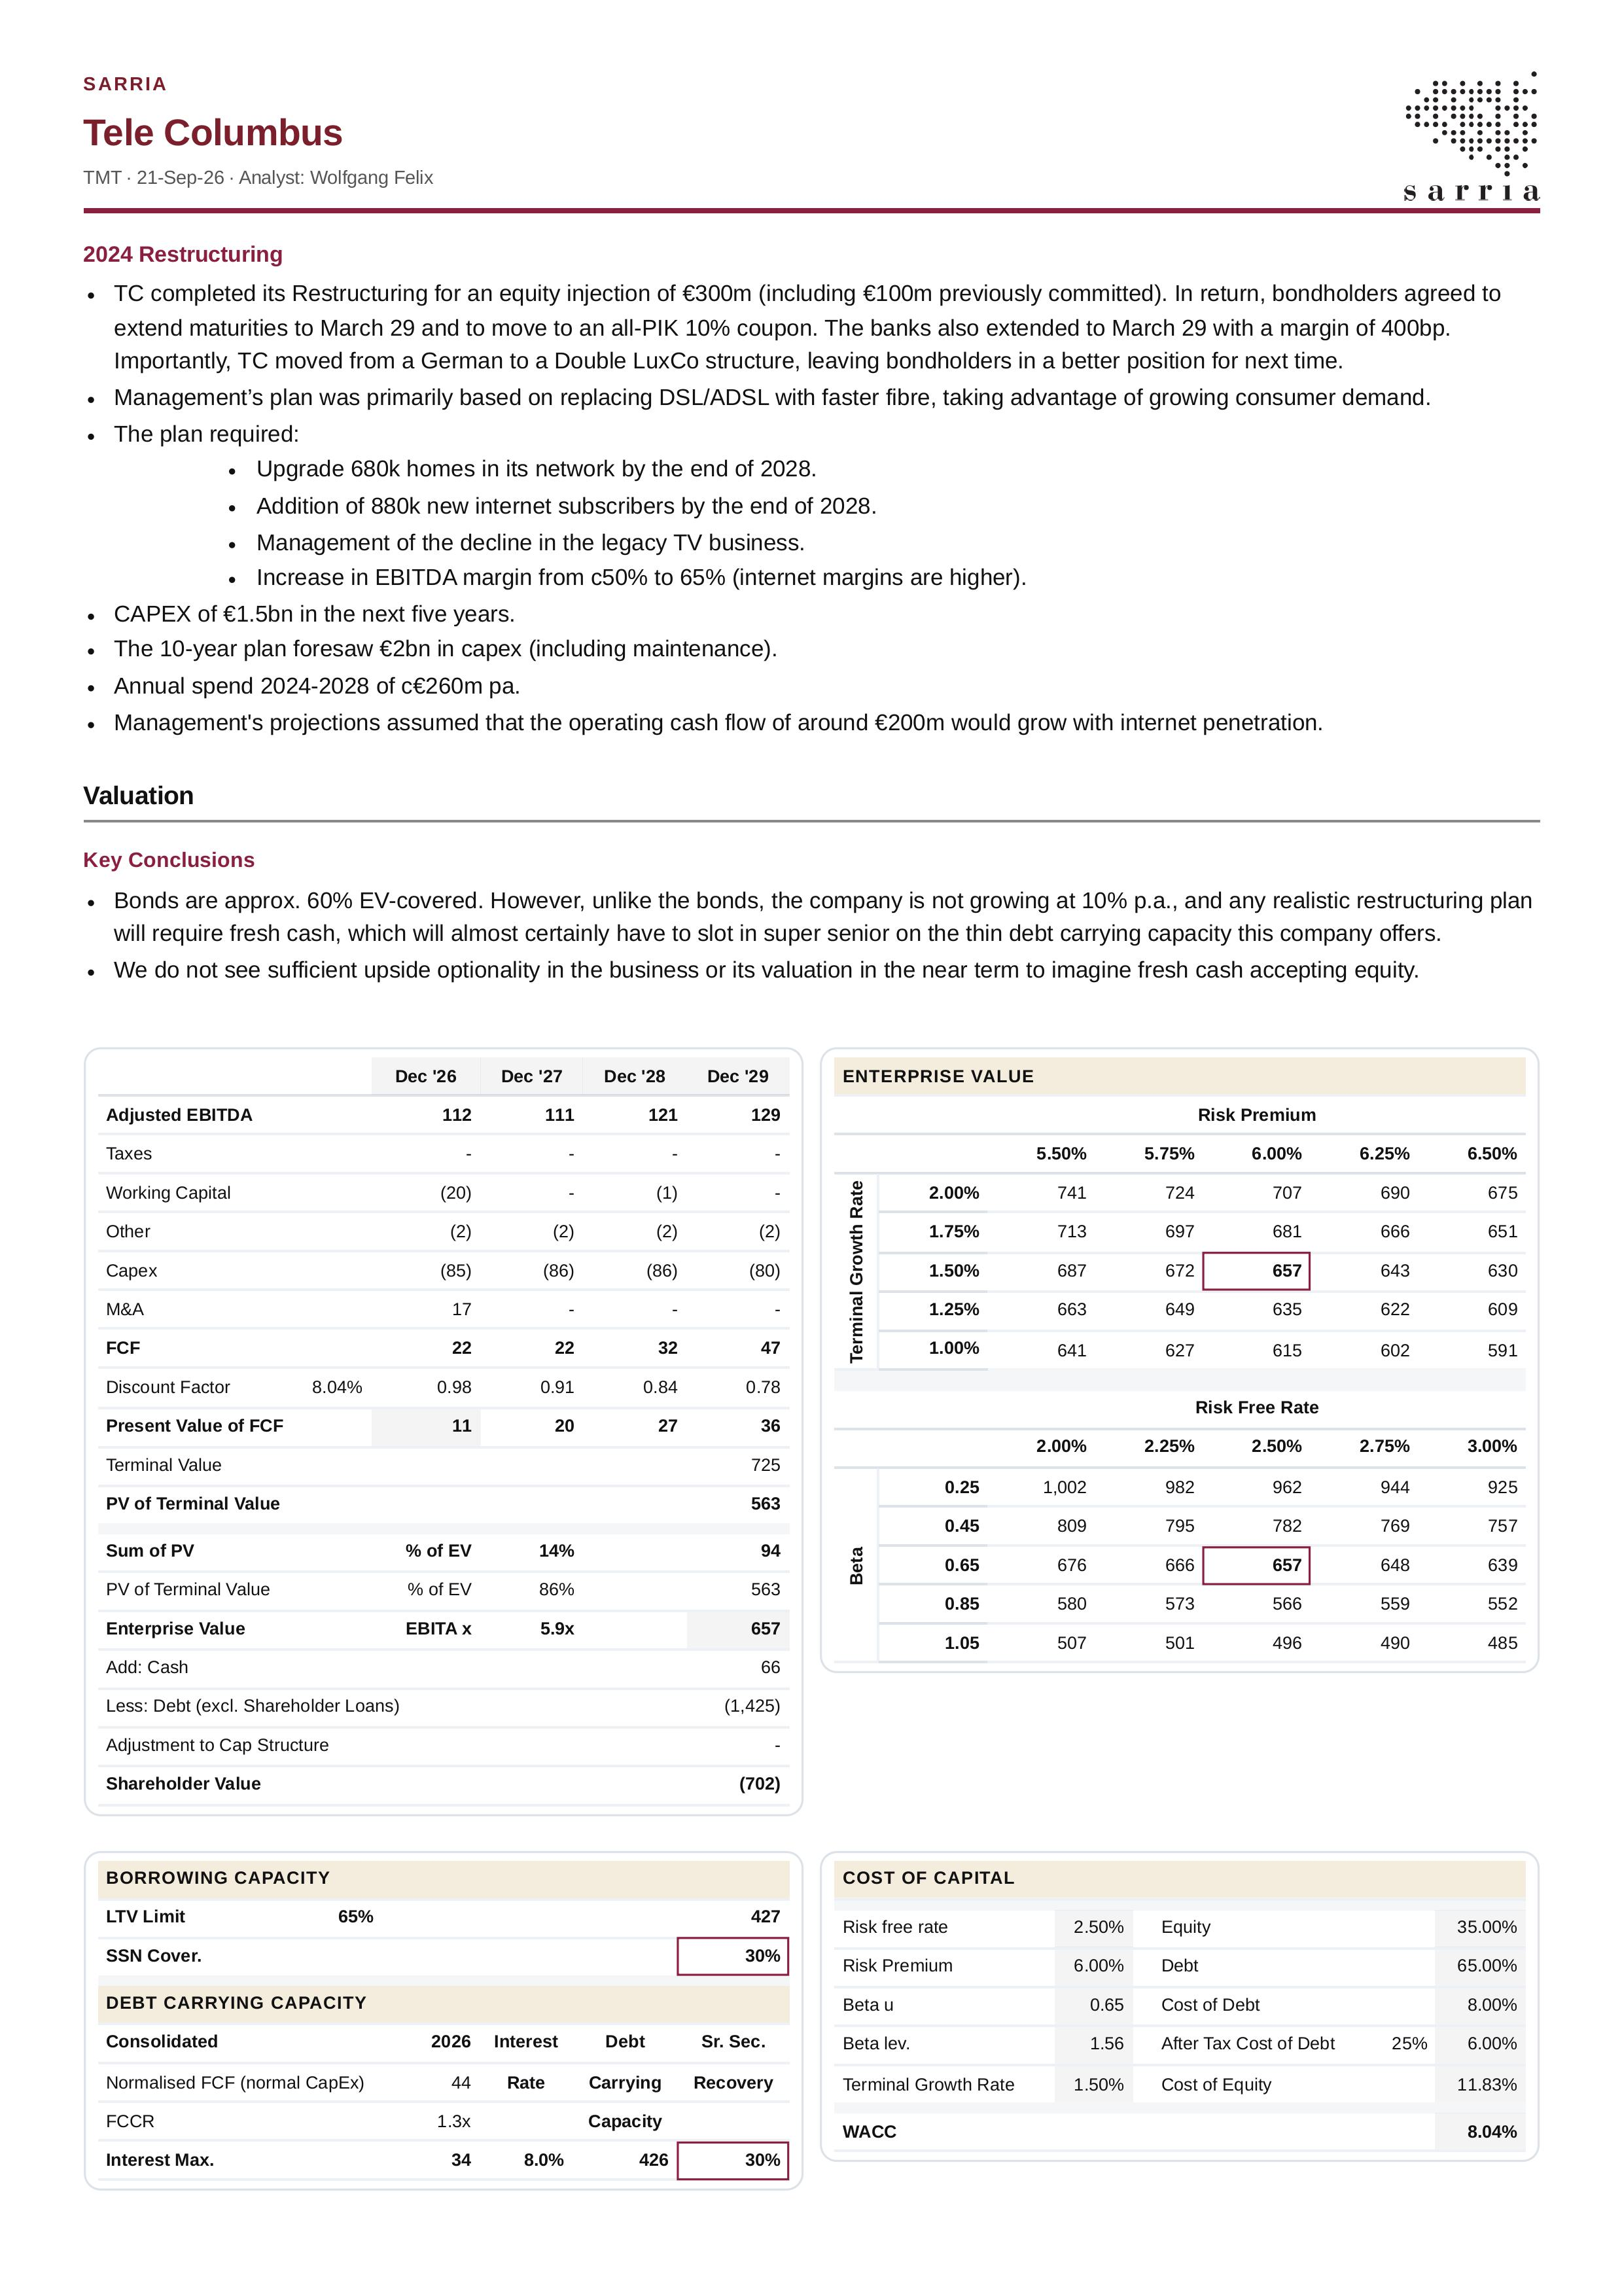
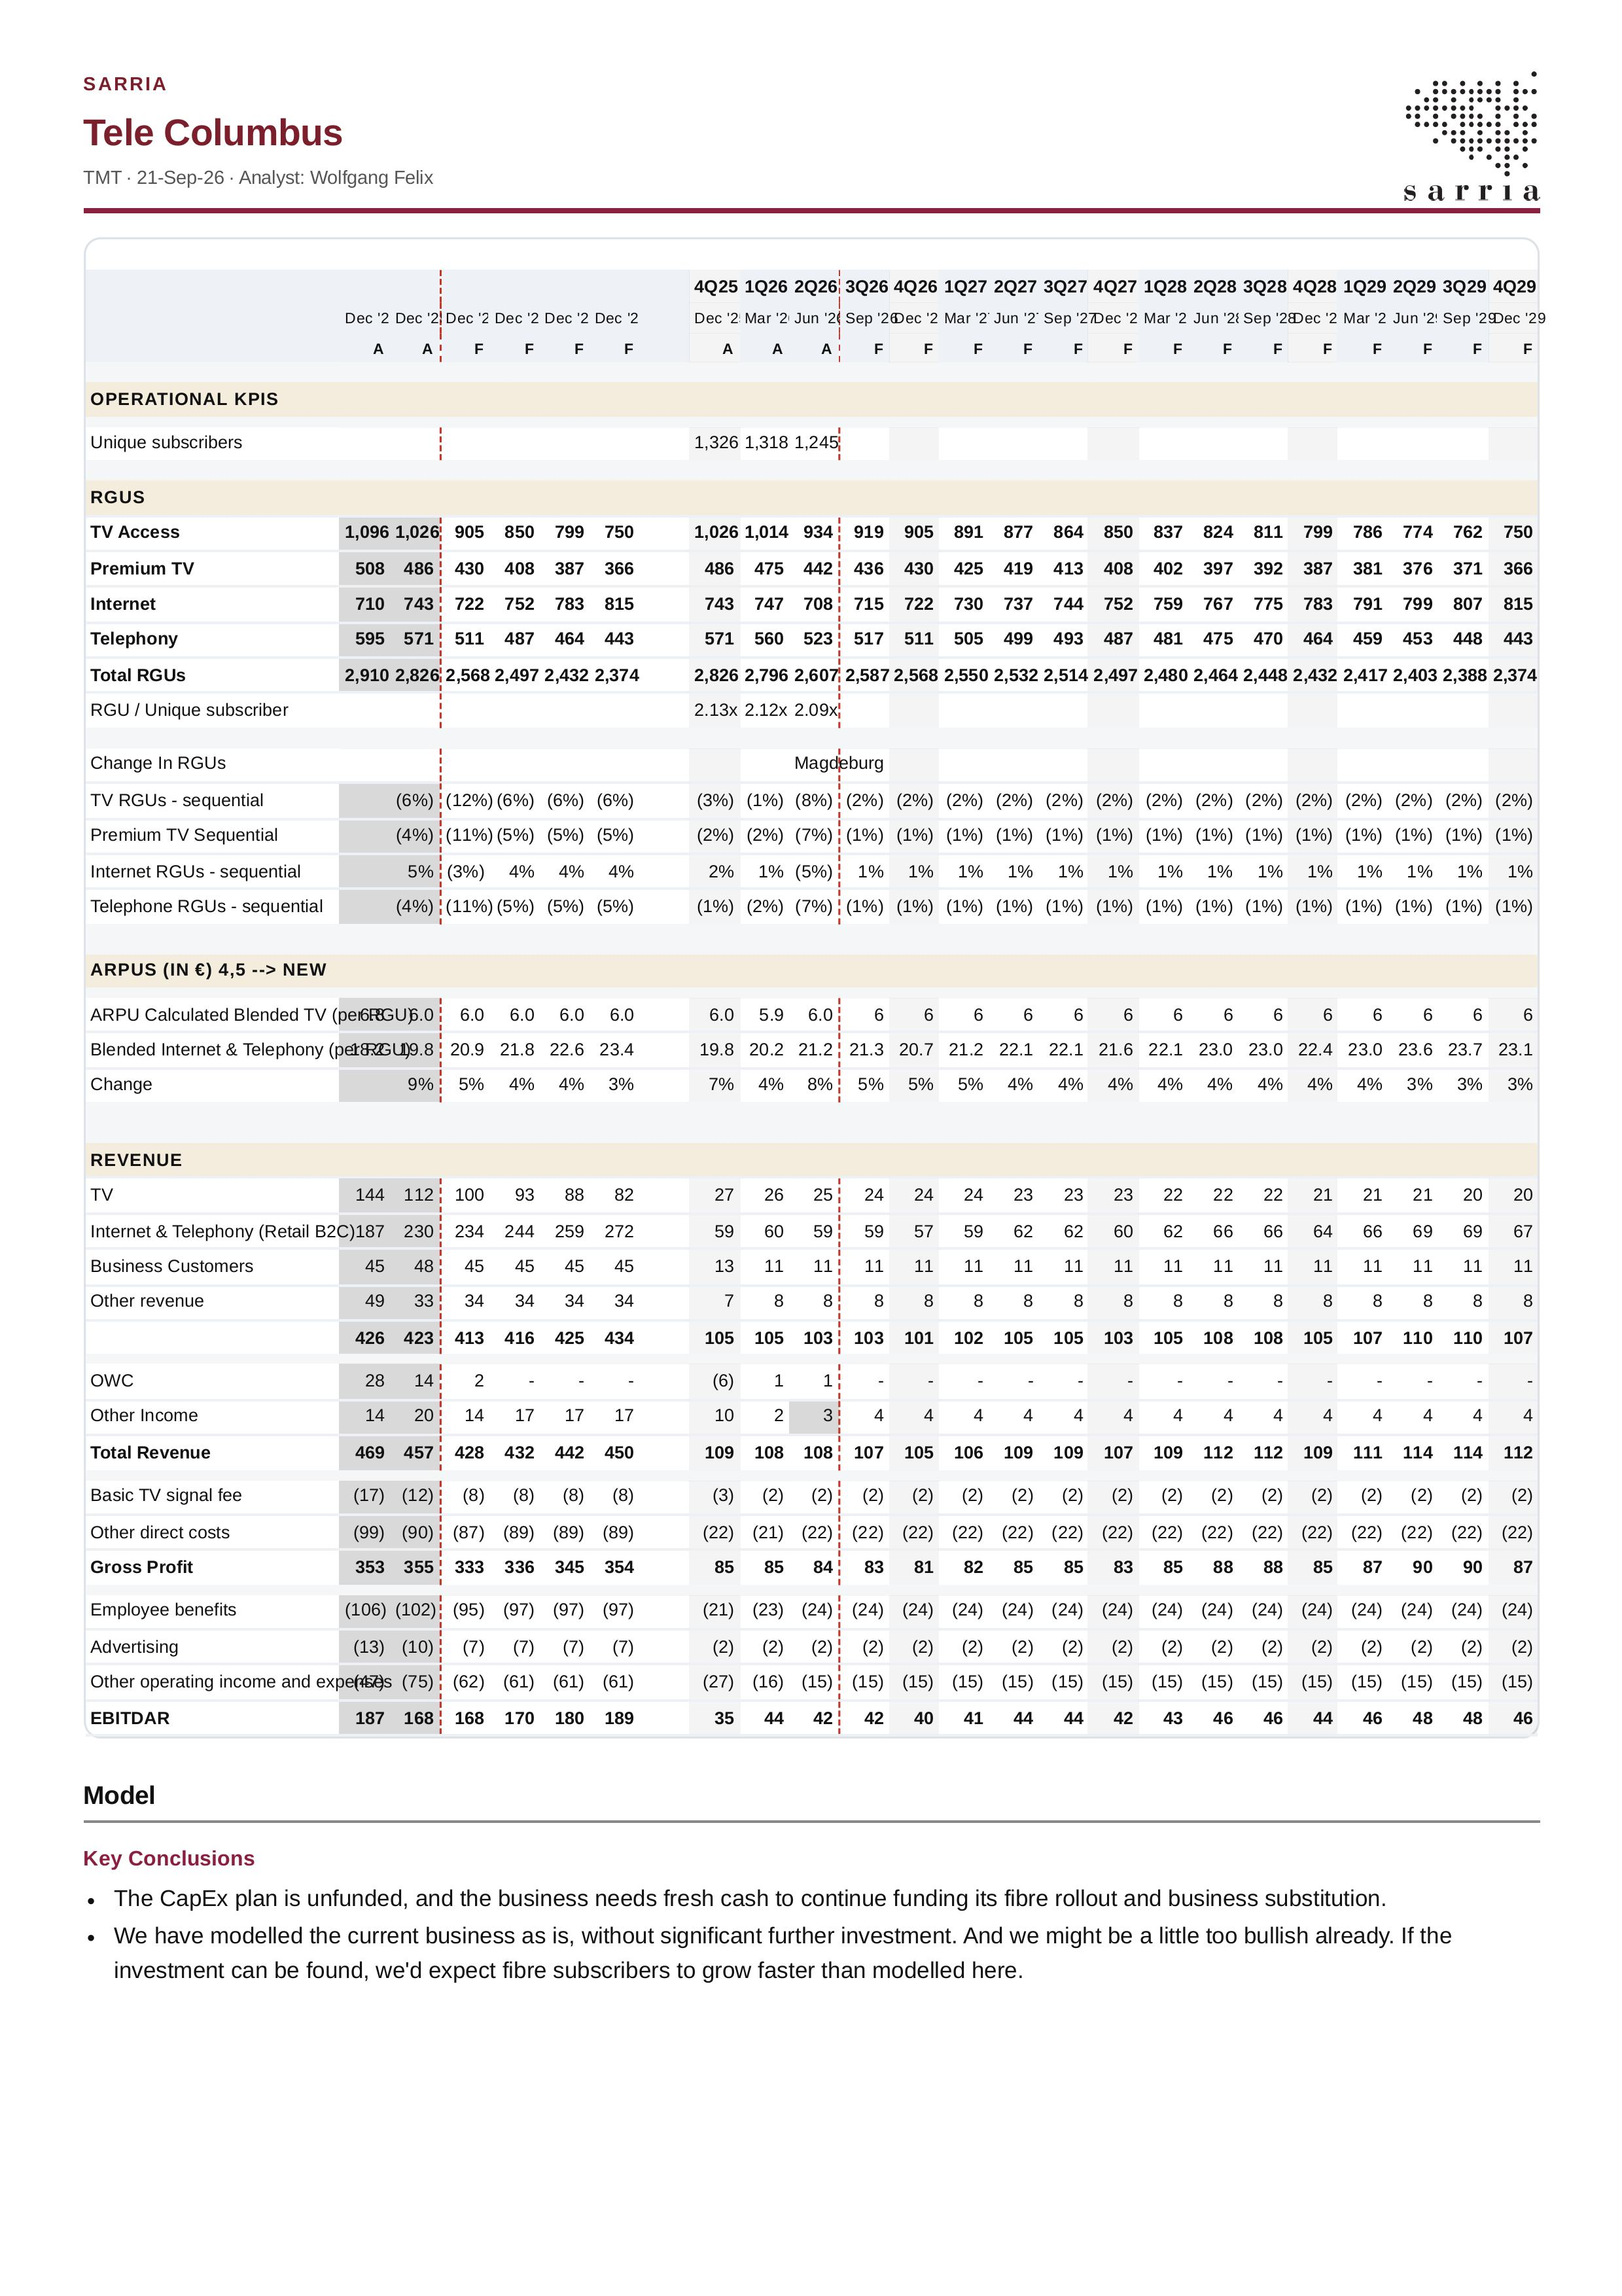
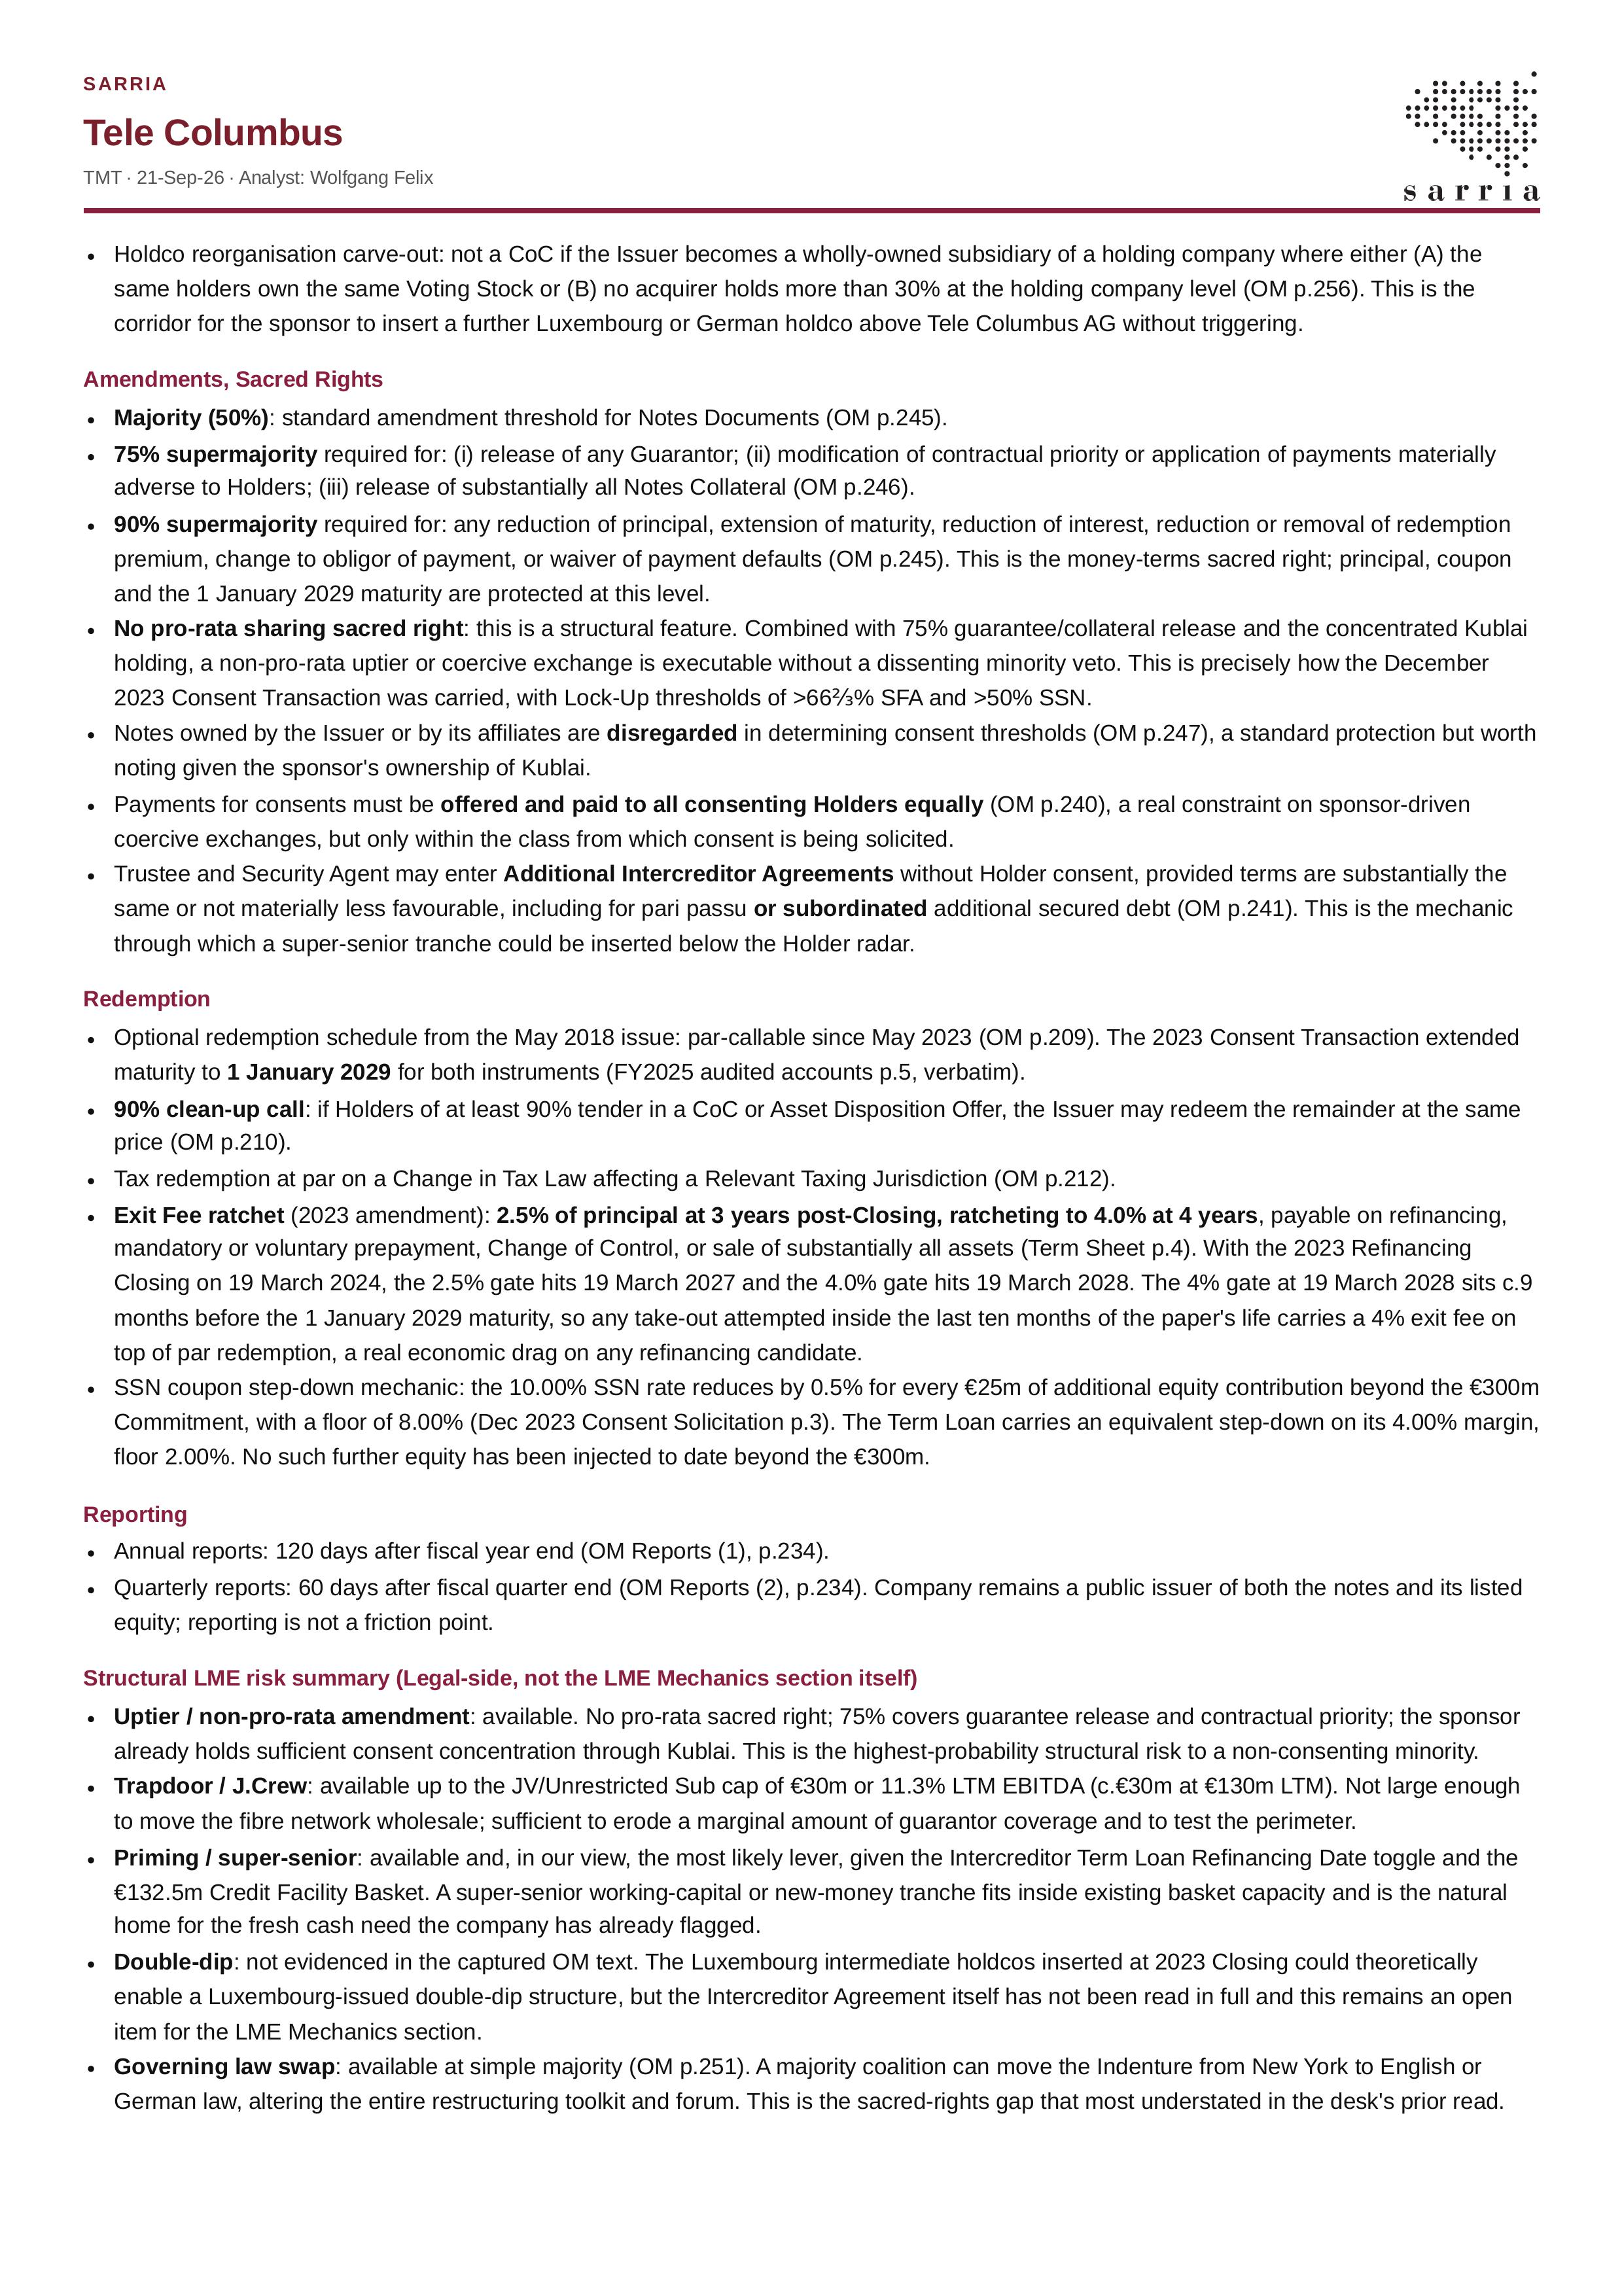
Company, Model and Valuation - 12 Sep 23
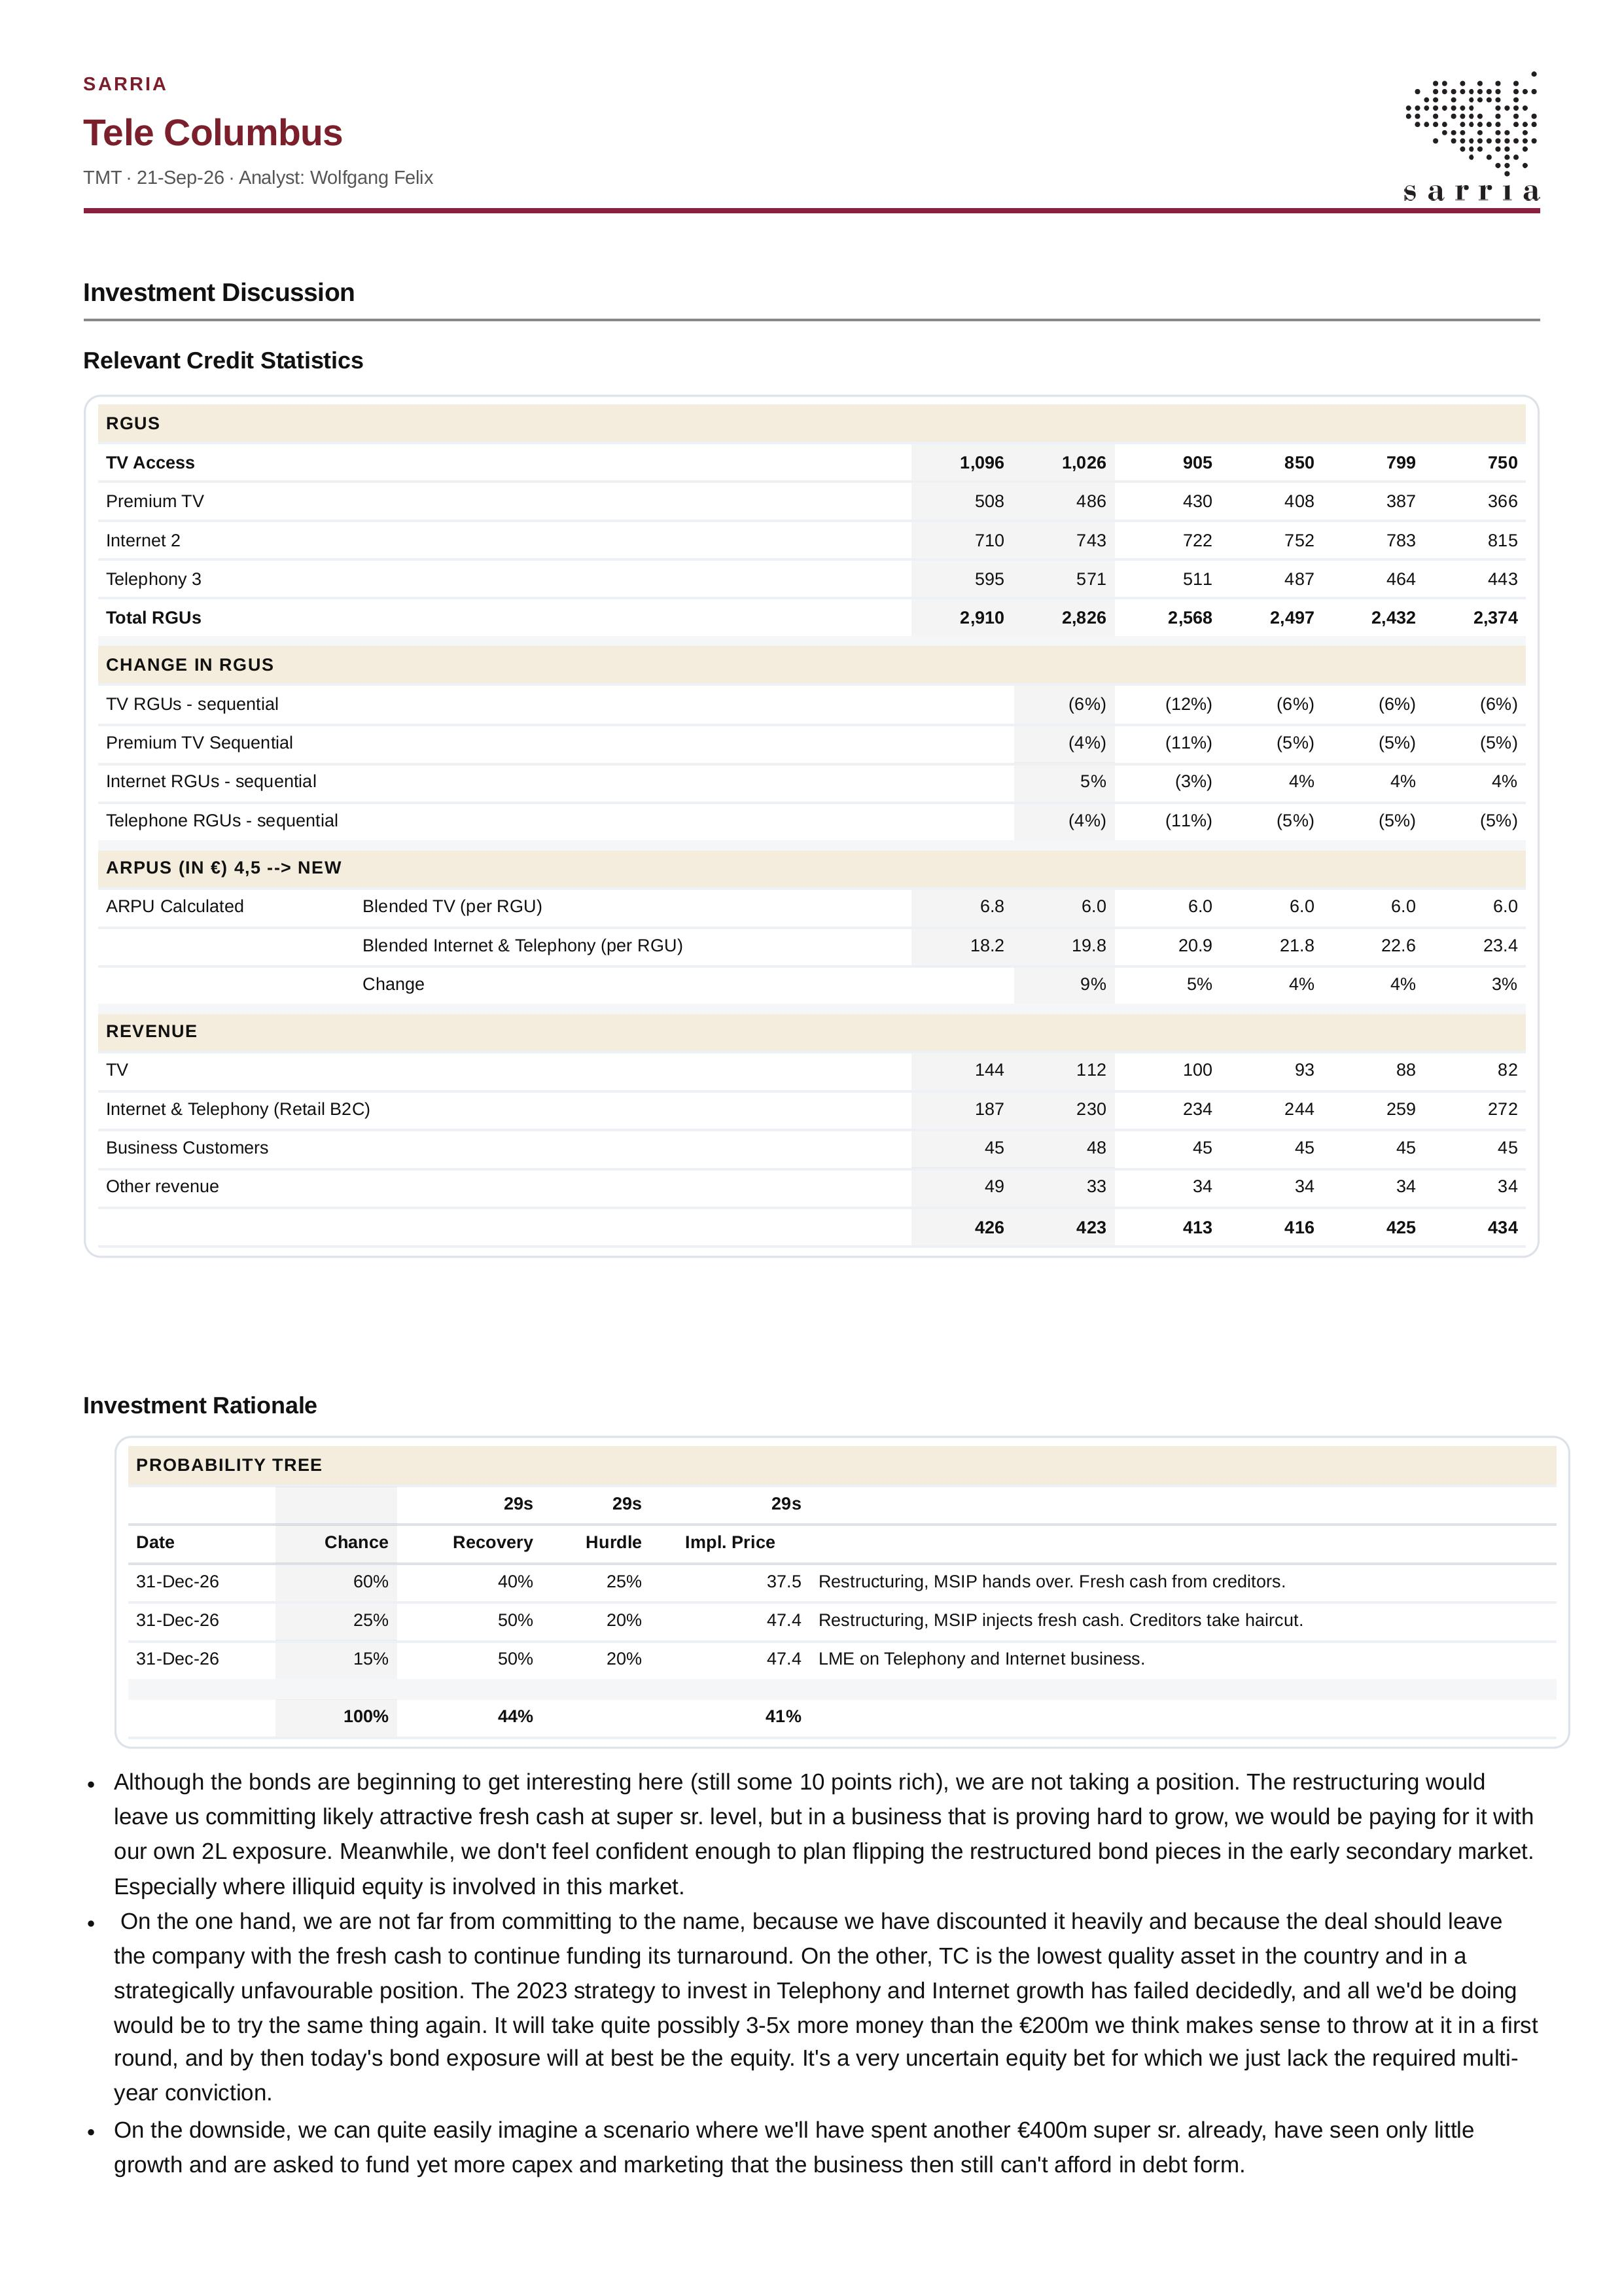
Investment Discussion - 12 Sep 23
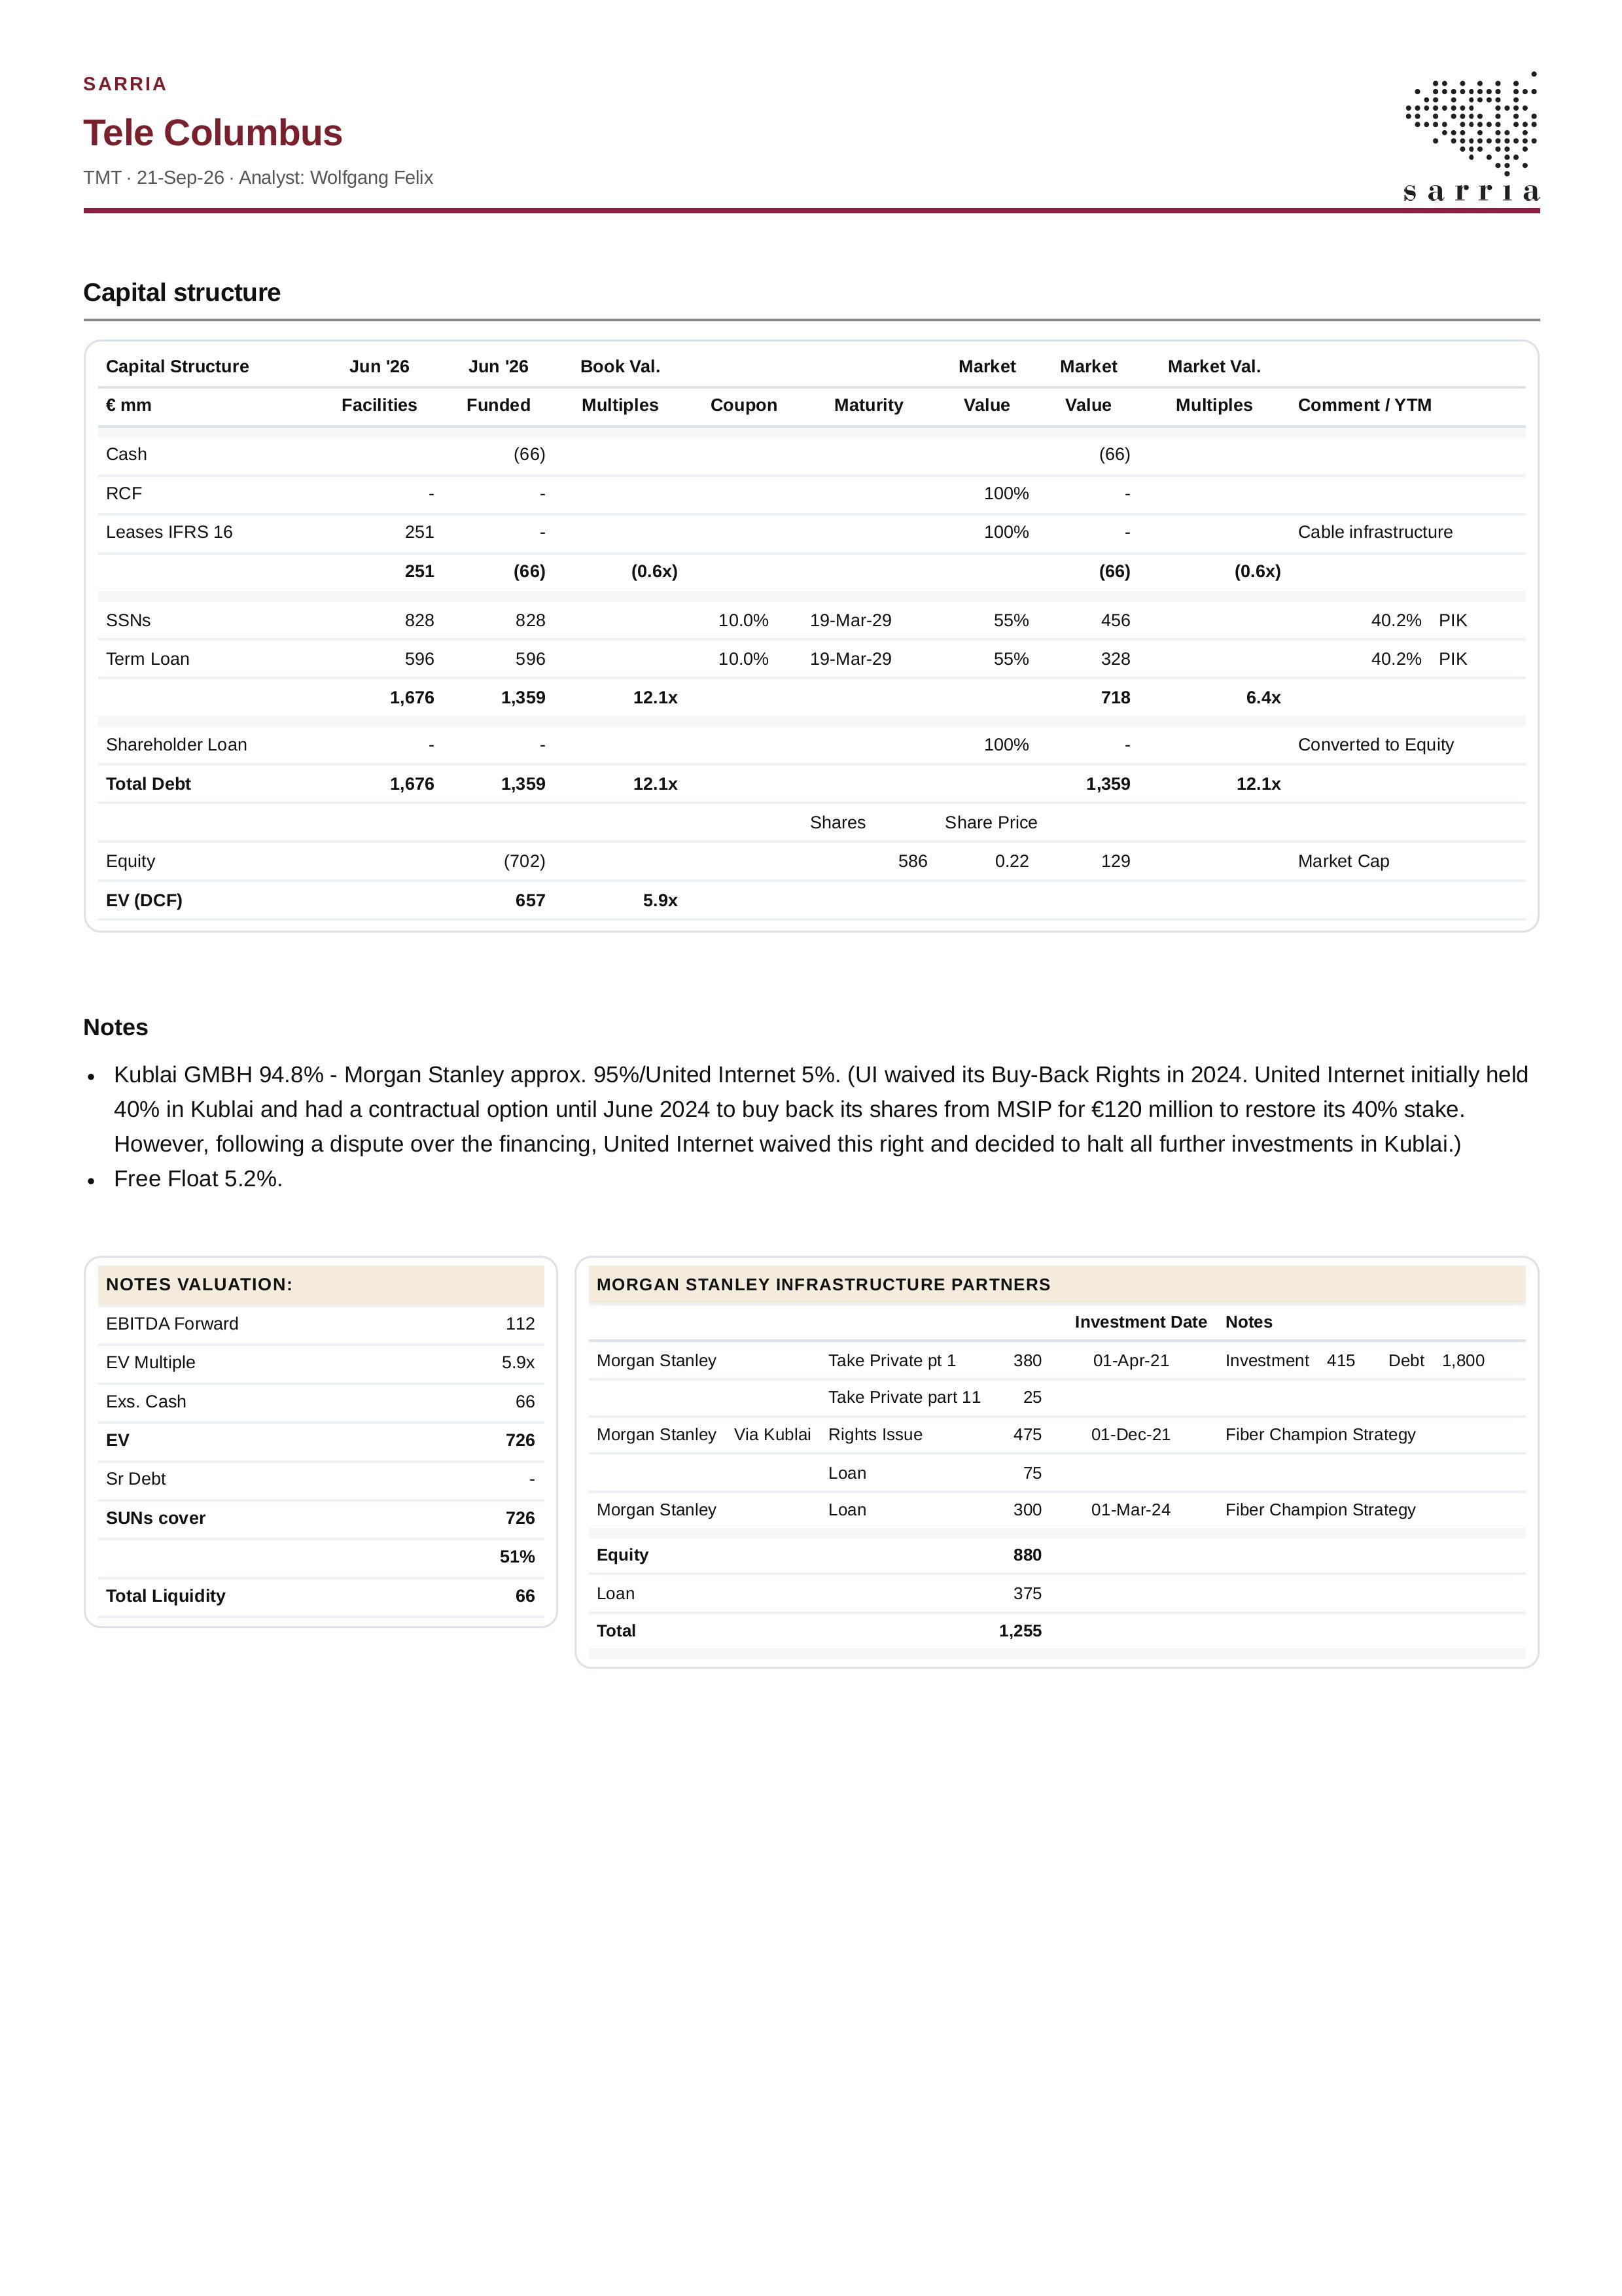
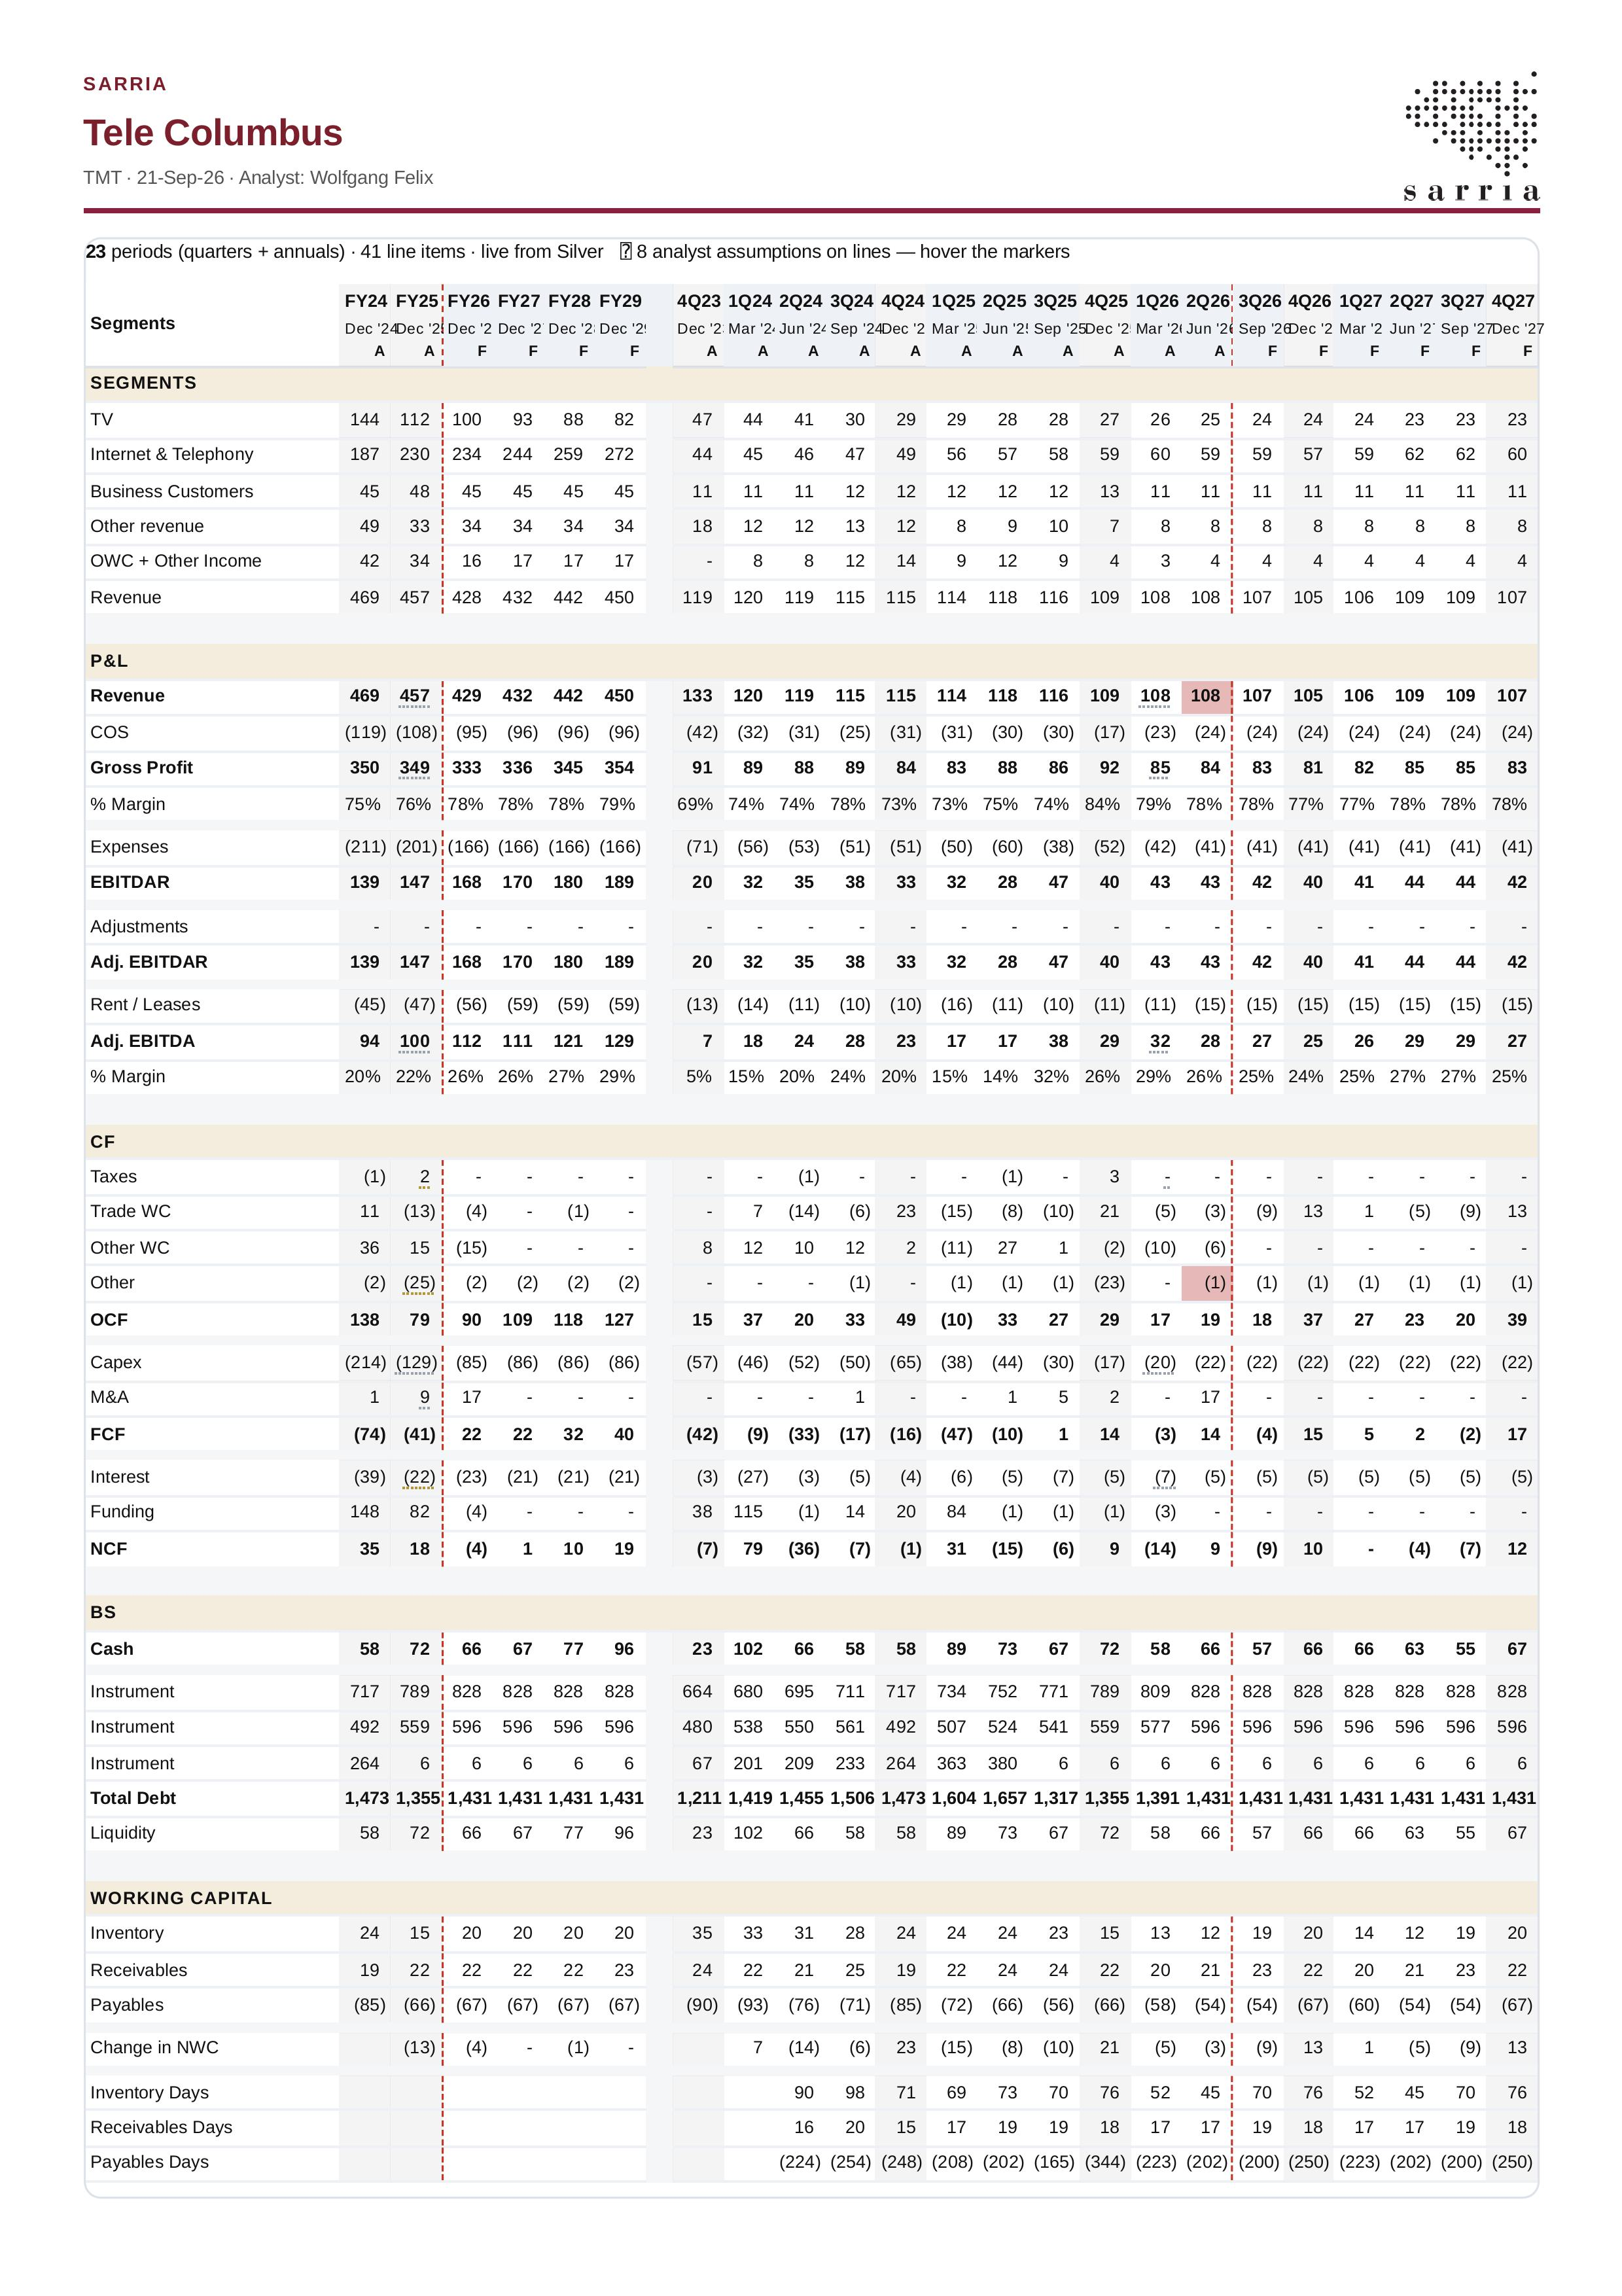
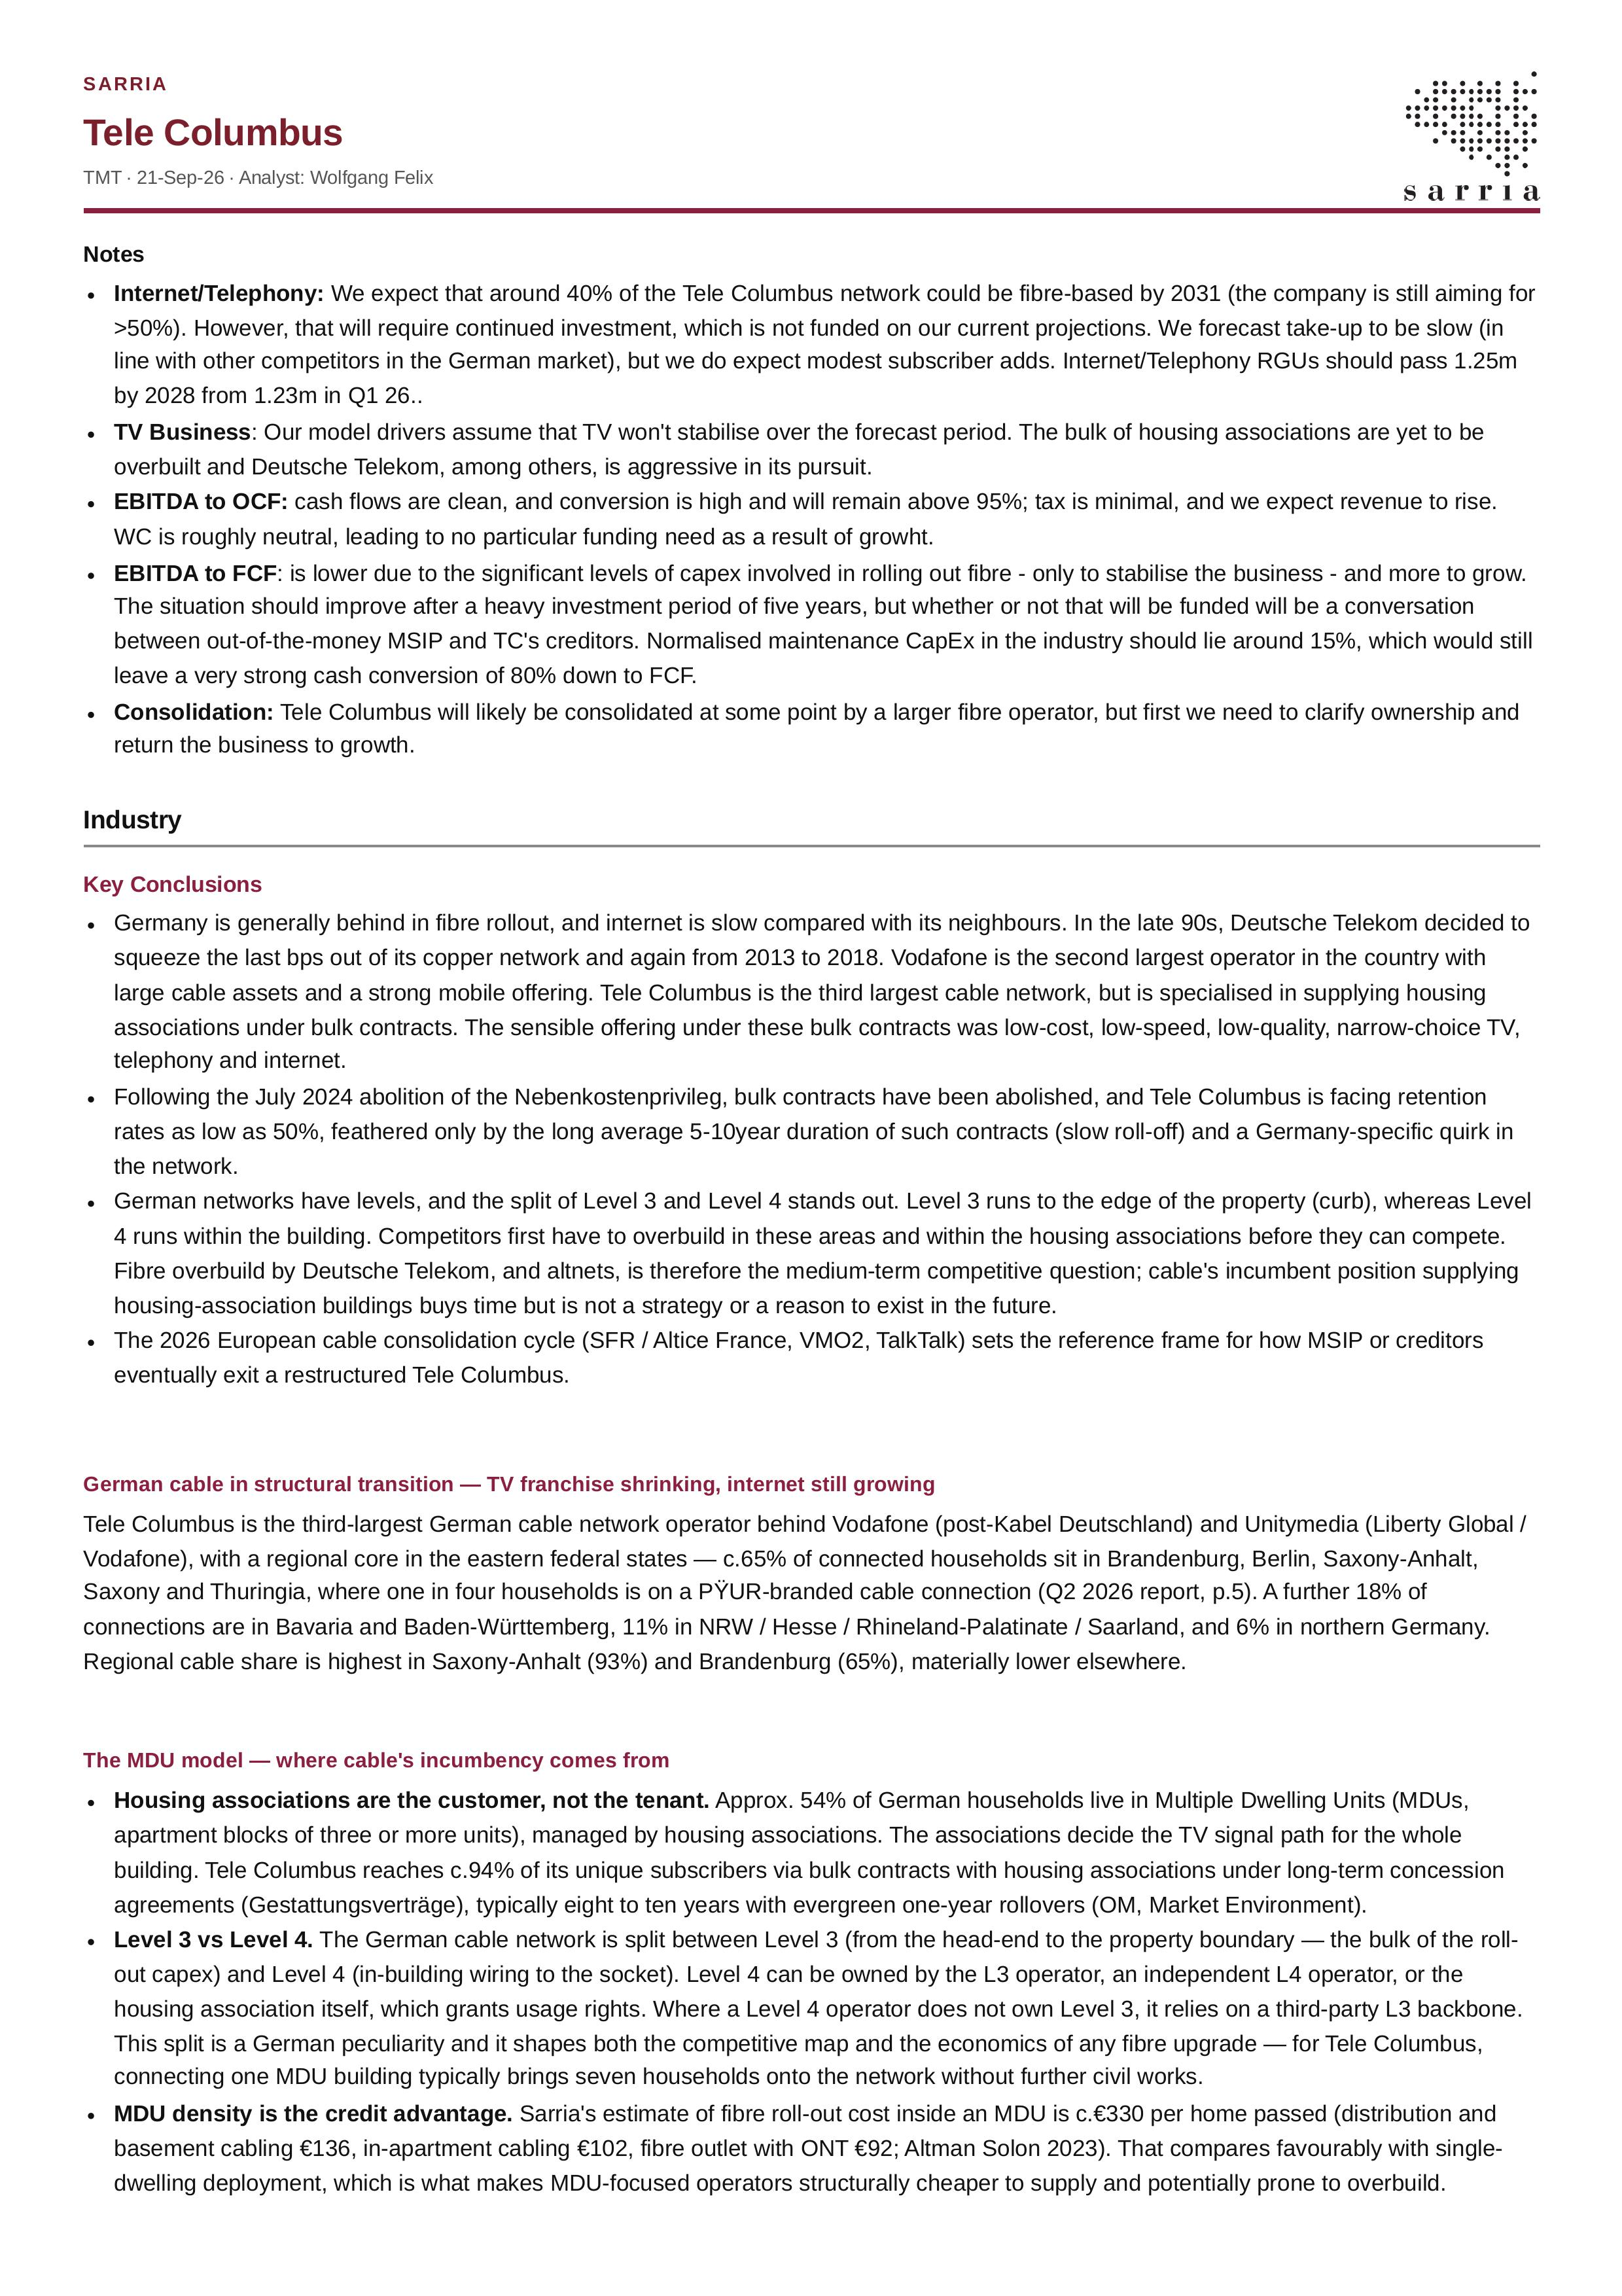
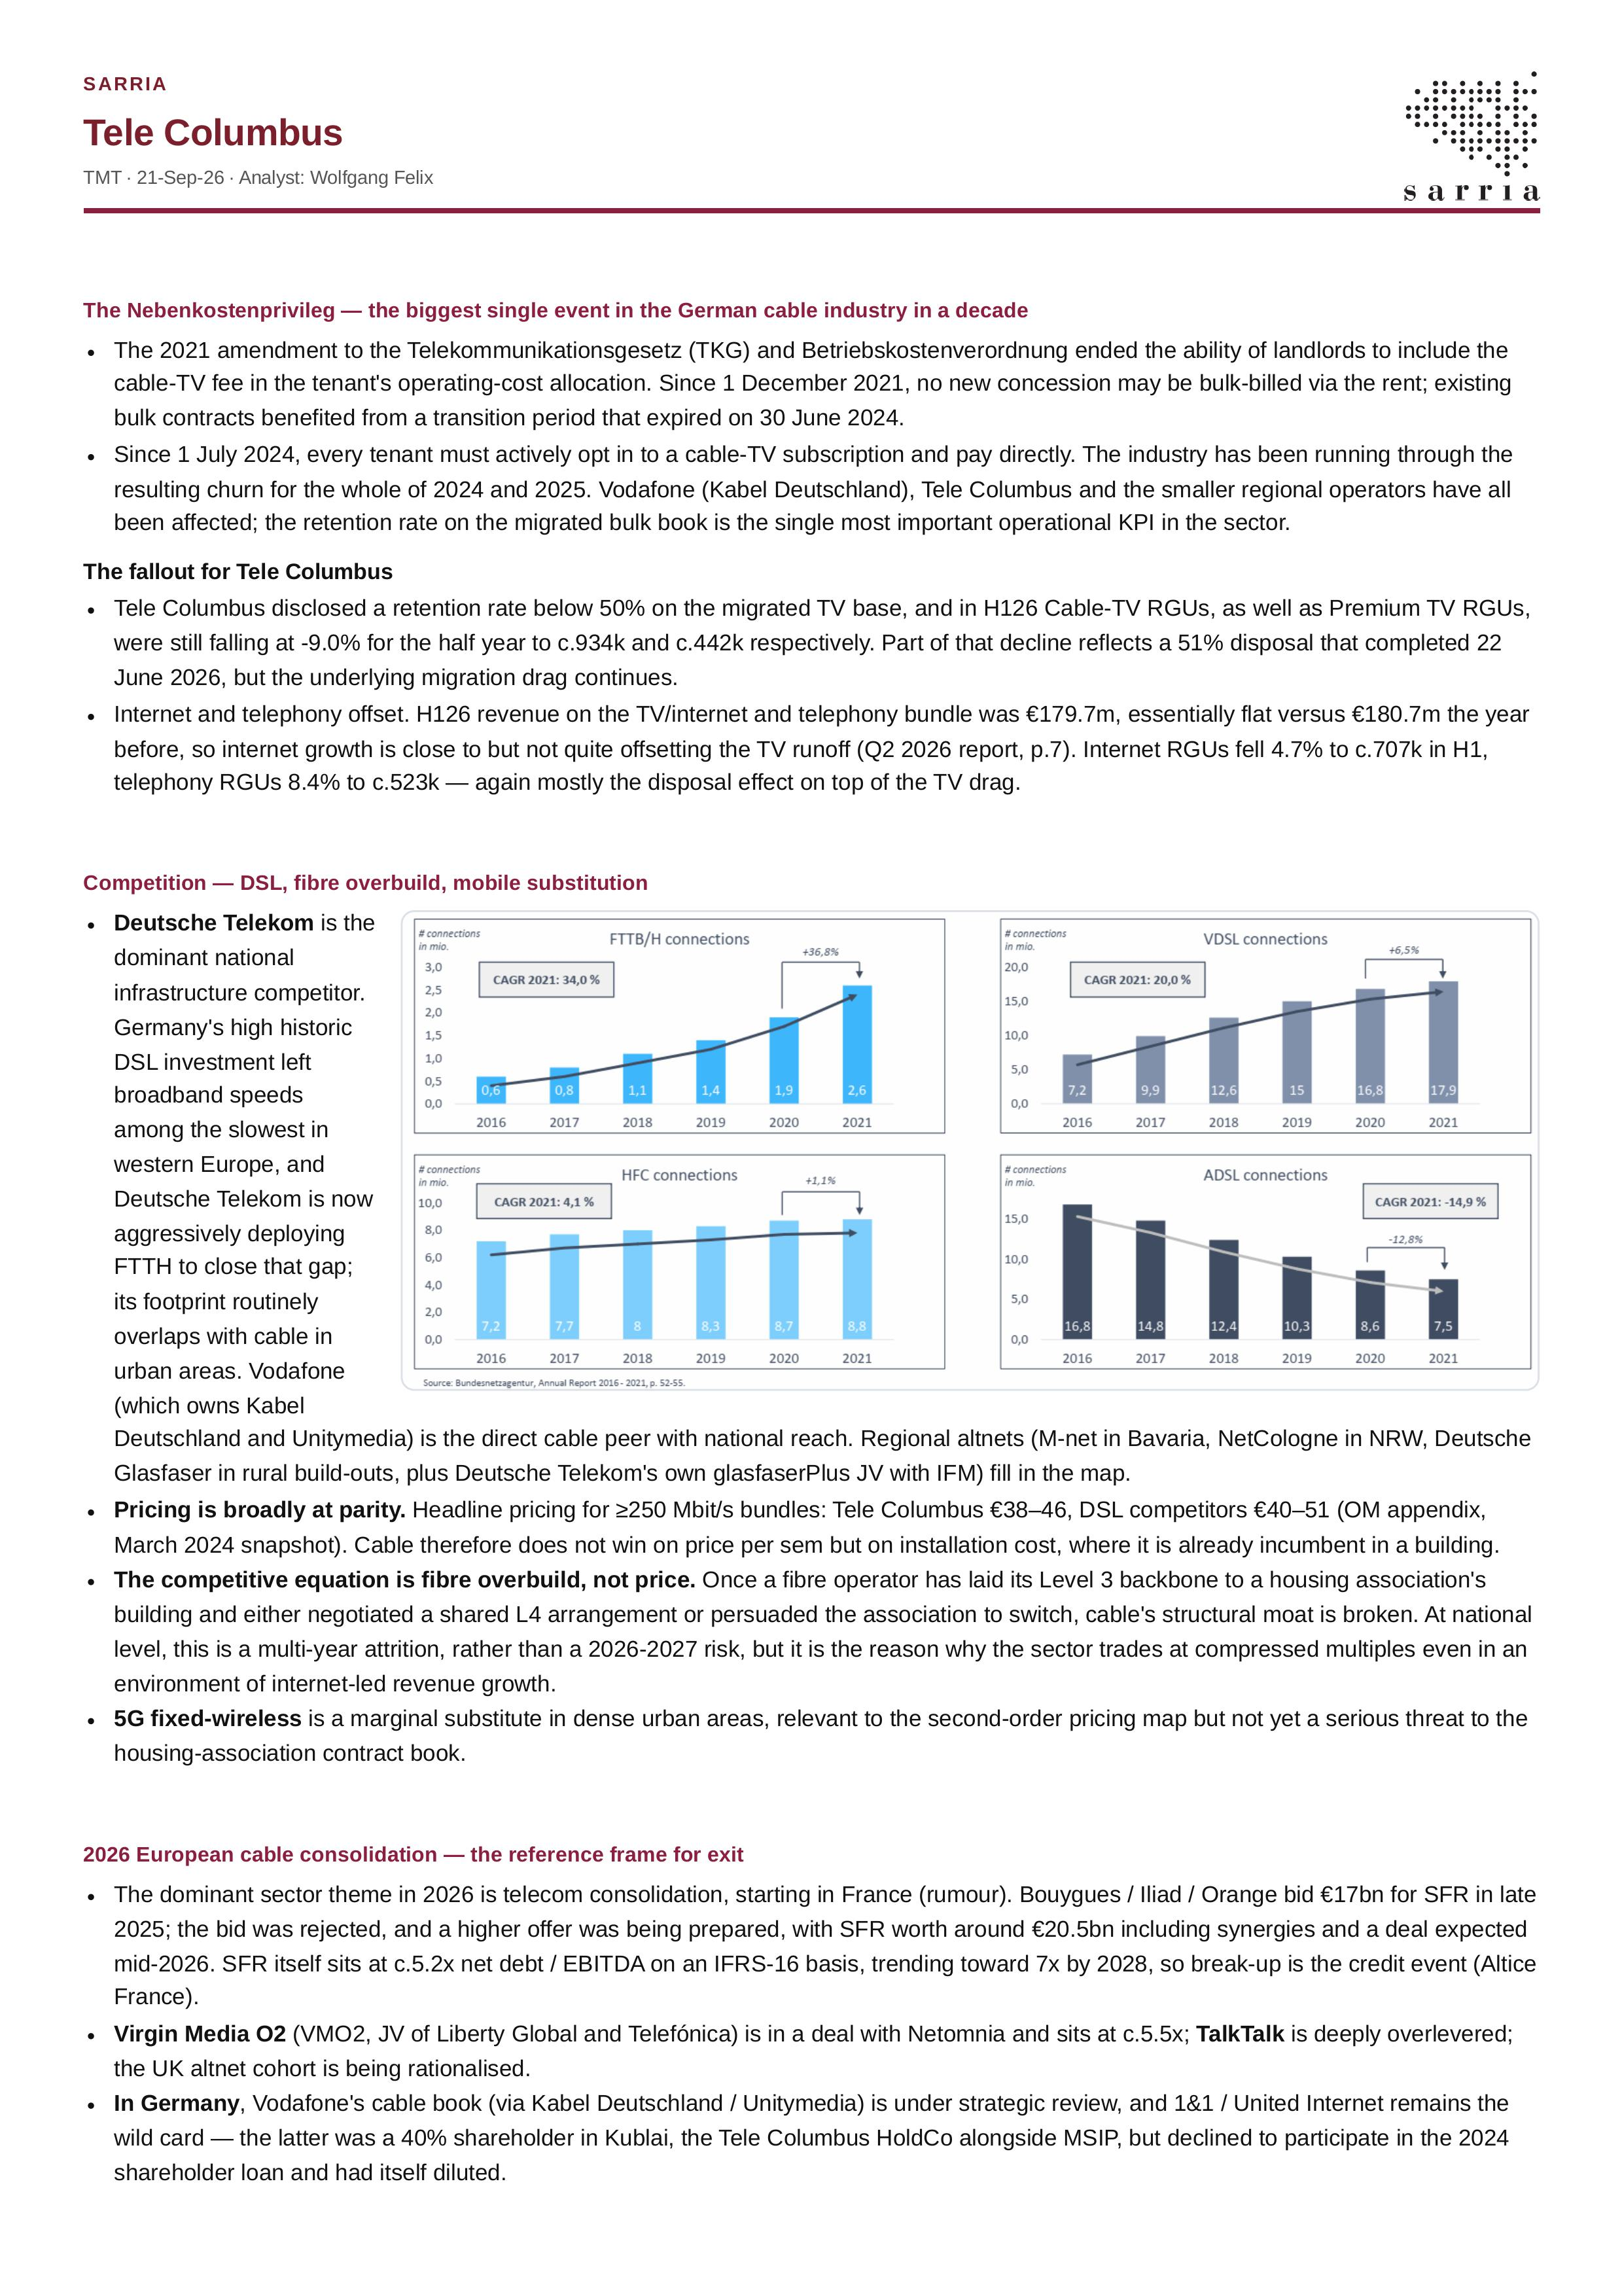
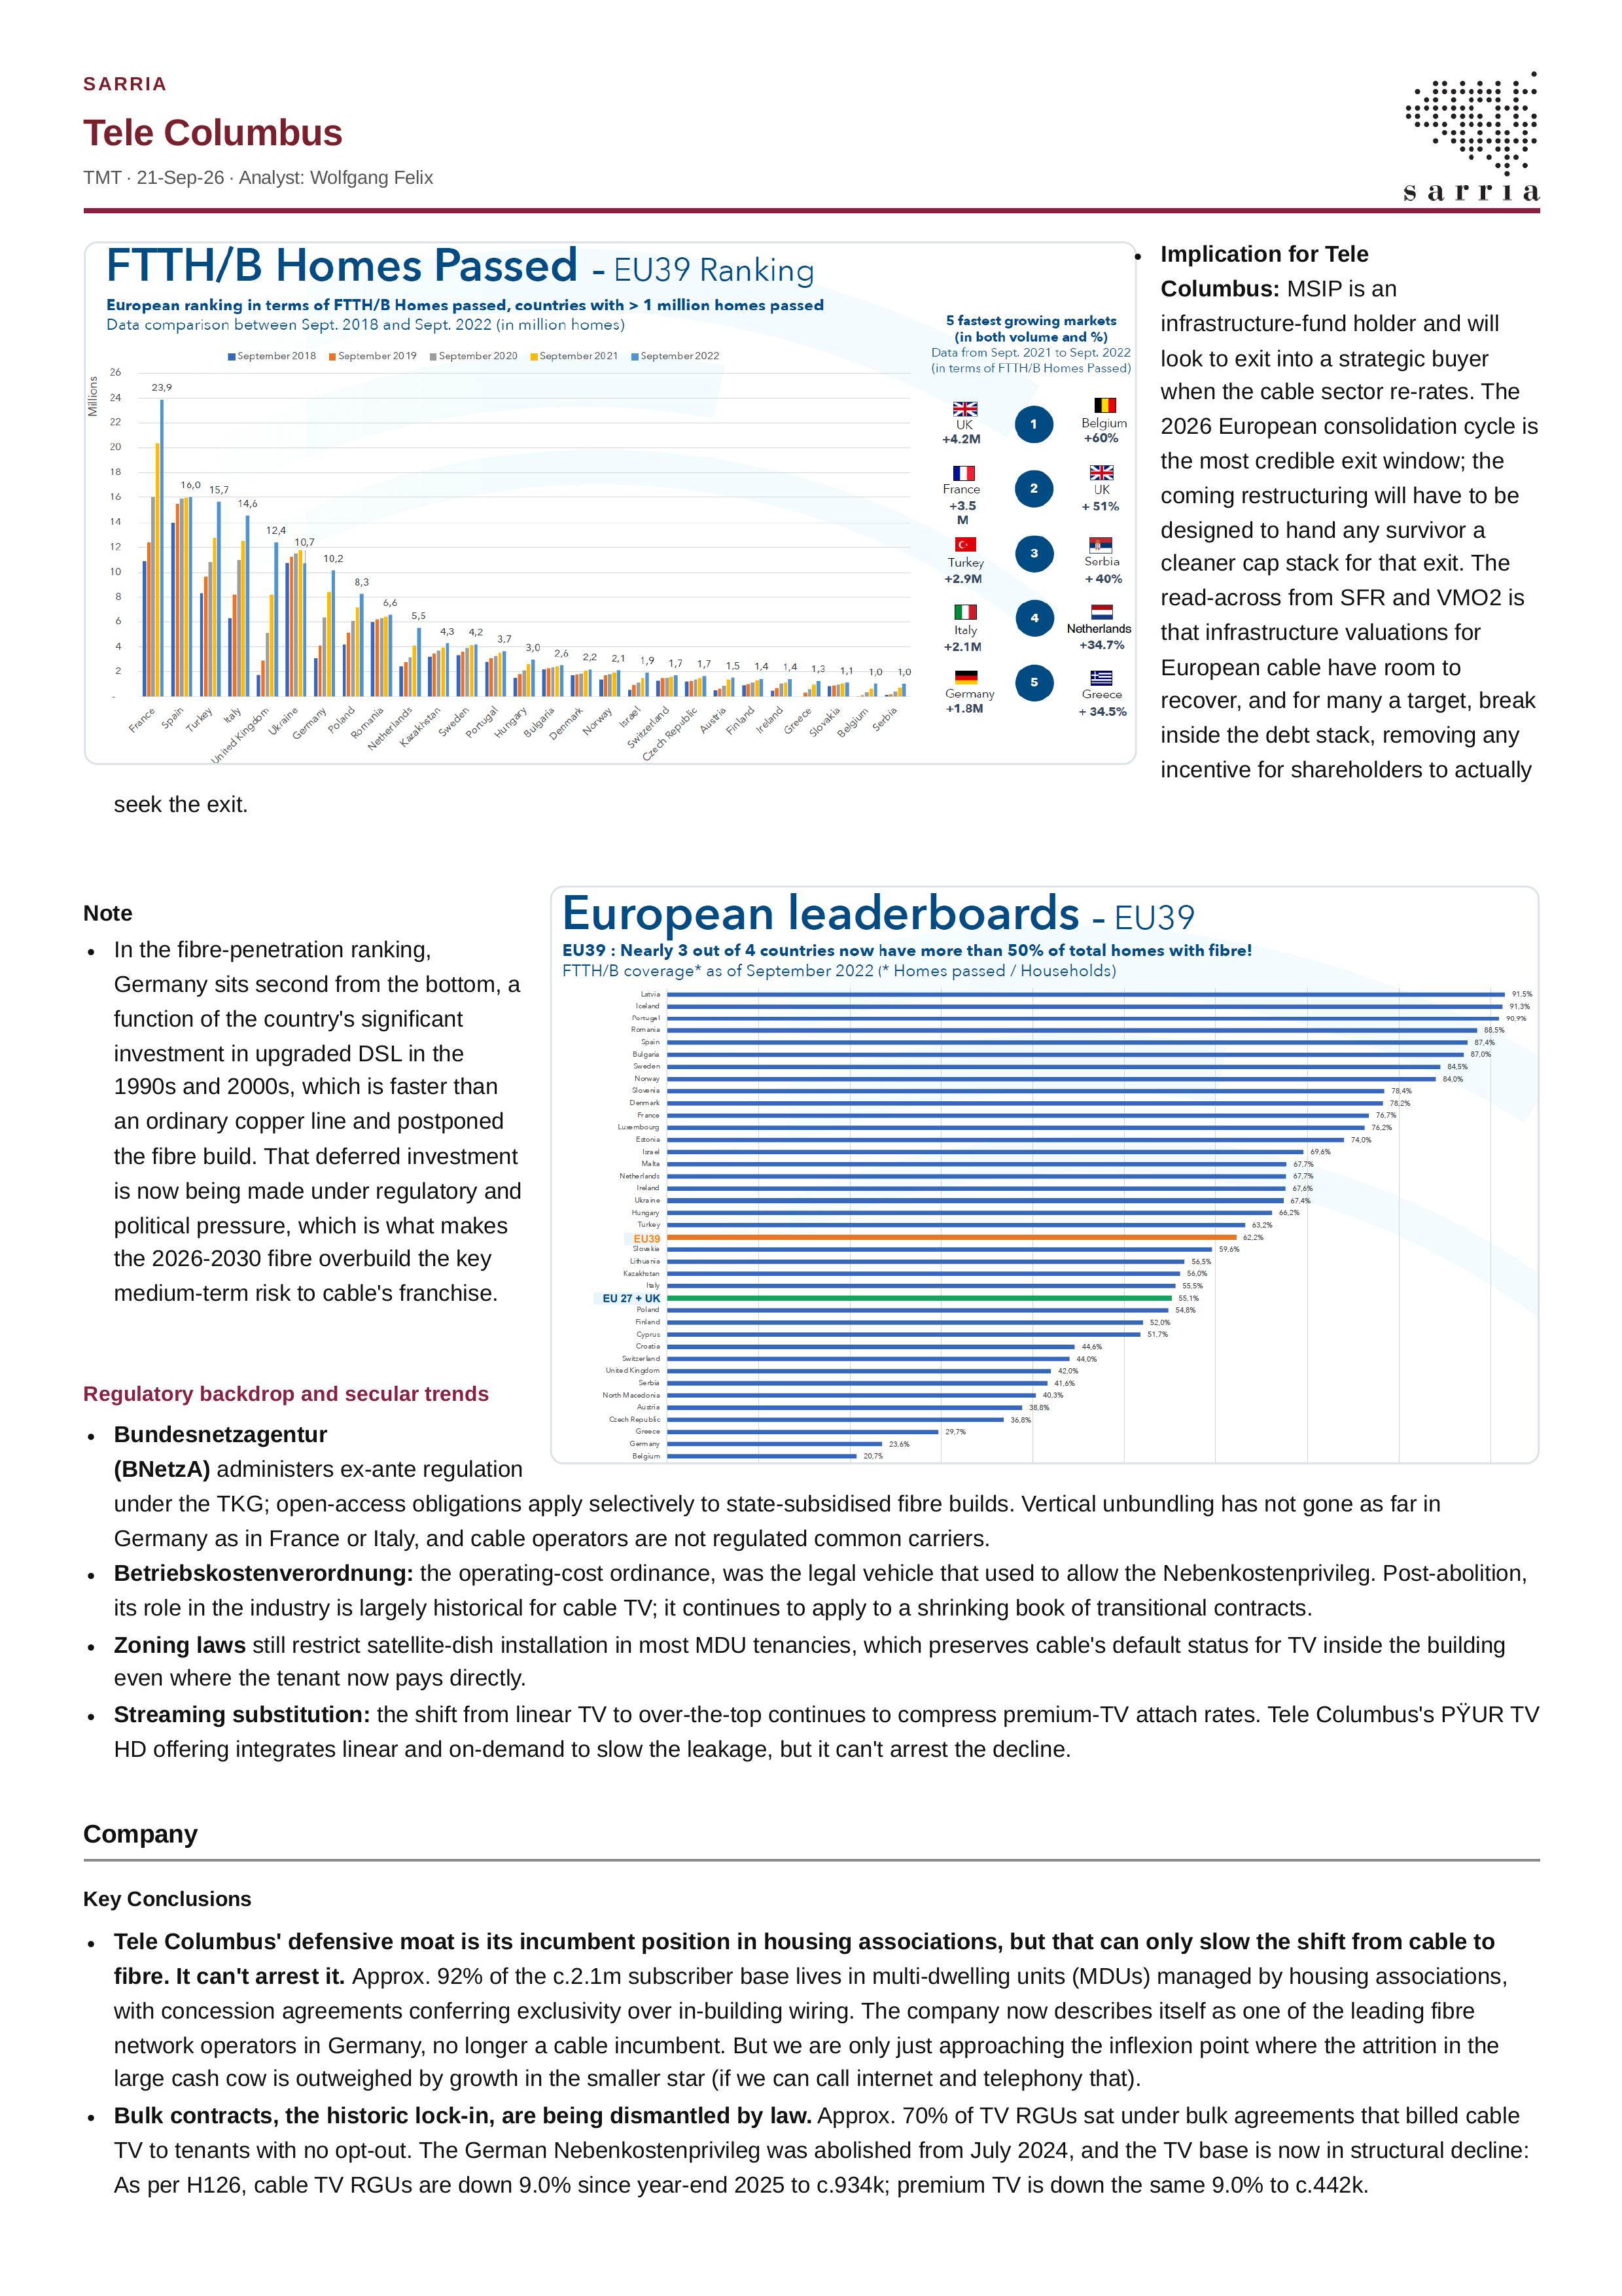
Please find our updated analysis of Tele Columbus here.
Are investors calculating off the right base? If you calculate your capex required to upgrade normal hotel rooms so that more travellers choose your hotel over others, you'd come up with a small number. A few extra amenities will do. However, it turns out the same is not true for convincing inmates. Once you allow inmates to choose among hotels, they will not choose based on their cell, but compared to other hotels available, and converting the prison into a competitive hotel is a larger relative capex outlay than adding a minibar and wifi.
Sounds trivial, but the generalised economics we hear thrown about that reason on ratios and averages just don't seem to apply to a hostage situation where there is more ground to be made up underneath the sheer numbers. Relative to TC's current shape, we might just need a lot more cash than shorthand economics would usually prescribe.
Tele Columbus is reporting "constructive dialogues between MSI MorganStanley and [its] lenders. The discussions are ongoing, and
Please find our updated analysis here.
Tele Columbus needs to restructure its balance sheet. The amount of cash needed to fulfil its capex plan is modest, but the company will never grow into its
The 2025 FY results are in line with our forecasts, which we believe were lower than market expectations. As a result, the bonds will be a
0% of Tele Columbus’ SSN holders signing up to the creditor co-op agreement is a positive for the bonds. Tele Columbus is close enough to the
The SSNs will be marked lower after news from Debt Wire that a majority of creditors in the Bank debt and the SSNs have signed a
The new CEO has a big job ahead of him. The take-up of new fibre services has been slower than hoped, and Tele Columbus has
Markus Oswald is leaving his job as CEO of Tele Columbus after only three years, without a successor in place. He has overseen the
Revenue was in line with our model, and whilst reported EBITDA was ahead, driven by the absence of one-offs. The take-up of new, faster
Please see our updated analysis here.
As we feared, Tele Columbus (TC) is struggling to get traction in upgrading its network and signing up customers. We forecast a funding gap
Partnering with a wholesale fibre provider will help manage the costs of the FTTH rollout in Berlin, so this is a small credit positive.
The numbers point to some progress in adding customers, with 2025 guidance pointing to additional, if slow, progress. The company forecasts flat revenue in
TC will need to start adding premium TV and Fibre customers quickly over the next few quarters to stay on track, but so far the revenue fall is
The EU court rejecting a challenge to the Vodafone acquisition of Cable assets 6 years ago was always the likely outcome. DT’s re-emergence as
The Q3 6.2% loss of TV customers from MDUs at Vodafone (Germany) can be applied to TC. The drop is sharp, but the downward slope from
Q2 24 revenue aligned with our forecasts with OCF €20m below our forecast of €155m. TV RGU losses and Broadband adds were in
From today, the bundling of TV fees into rent has been abolished. The suppliers have been aware since 2021, but from now we will see how ready the
United Internet (UI) potentially suing Morgan Stanley (MS) over its valuation of Tele Columbus (TC) should not distract management as they will still get the
Please find our slightly updated analysis here.
Tele Columbus (TC) has completed its restructuring and can now concentrate on building its fibre network and protecting its CATV business. There is a
24Q1 revenue and adjusted EBITDA were in line with our modelling. The cap markets day was last week, and management gave a steer for today’s figures, so there were